What Happens to Your Mortgage When the Home Has an Unfinished Addition?
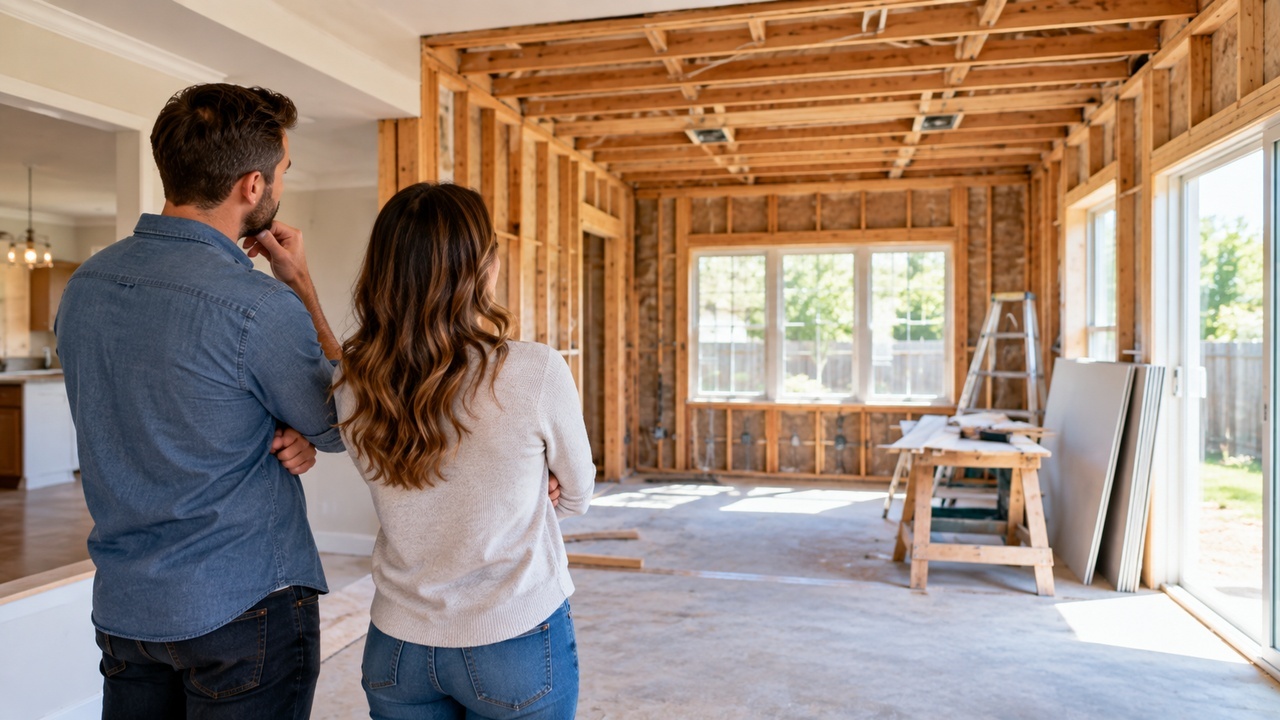
You find a home you love, but there is one unusual feature. Maybe the previous owner started adding a bedroom and never finished it. Perhaps a bathroom is partially remodeled, a garage conversion is incomplete, or a new section of the house is still visibly under construction.

Buyers may see opportunity in unfinished space, but a mortgage lender may need to evaluate the property as it exists today.

Financing Is Based on the Current Property
It is easy to walk through an unfinished addition and imagine what it could become.

The mortgage transaction, however, generally has to consider the property’s current condition rather than simply the buyer’s plans for completing it later.

The appraiser may need to identify unfinished areas and determine how they affect the property being valued.

Not All Unfinished Projects Are Equal
Missing cosmetic finishes are different from major incomplete construction.

A room awaiting paint or updated flooring presents a different situation than an addition with exposed framing, unfinished electrical work, missing plumbing fixtures, or other incomplete components.

The extent and type of unfinished work can influence what questions need to be answered.

Permits Can Become Part of the Conversation
An addition also raises another important question: Was the work properly permitted when required?

Buyers should understand what was added, who performed the work, and what information is available through the seller or applicable local records.

An attractive partially completed space should not automatically be assumed to be recognized living area.

Do Not Assume You Can Finish It After Closing
Buyers sometimes approach an unfinished project with a simple plan: purchase the property now and complete everything later.

That may ultimately be possible, but it should not be assumed before the financing has been reviewed.

Depending on the property condition and mortgage program, incomplete work could require additional evaluation or affect available financing options.

If you are seriously considering a home with an unfinished addition, show the details to your mortgage professional as early as possible. Photos, listing information, disclosures, and information about the work can help start the conversation.

A half-finished room may look like an opportunity to create exactly what you want.

Just remember that before you can finish the project as the homeowner, you first have to successfully purchase the property in its present condition.
Why the Money in Your Bank Account May Need a Paper Trail Before Closing

Having enough money in the bank is an important part of buying a home, but during the mortgage process, the amount in your account may not be the only consideration. In certain situations, lenders may also need to understand where funds came from. That can surprise buyers who assume that once money reaches their account, its history no longer matters.
Mortgage Funds May Need to Be Documented
During the mortgage process, buyers may provide bank or asset statements showing money available for the transaction.

If an account contains certain recent deposits that are not easily explained by the documentation already provided, additional information may be requested.

The purpose is not to question every dollar a buyer spends or receives. Mortgage guidelines may require lenders to verify certain funds being used in connection with the purchase.

Moving Money Can Make Things More Complicated
Buyers sometimes reorganize their finances before purchasing a home.

They may transfer money between checking and savings accounts, move funds from an investment account, deposit proceeds from selling personal property, or receive money from another person.

Even when the funds are legitimate, multiple transfers can create more documentation because the movement of money may need to be traced.

Keeping records can make that process considerably easier.

Gifts Have Their Own Requirements
Some buyers receive financial assistance from an eligible family member or another permitted source.

Depending on the mortgage program, gift funds may be allowed for some or all of the money needed for the transaction. However, there can be documentation requirements regarding the gift, donor, transfer, and source of funds.

Do not assume that depositing a large check into your account is all that is required.

Avoid Unnecessary Financial Shuffling
Before closing, simplicity can be valuable.

If you are considering moving a large amount of money, making an unusual deposit, changing bank accounts, or receiving funds from someone else, ask your mortgage professional what documentation may be needed.

Save statements, transaction confirmations, deposit records, and other relevant documentation rather than assuming you will never need them.

Money being available and money being properly documented are not always the same thing during a mortgage transaction.

You do not need to stop using your bank accounts normally while buying a home. But understanding that certain funds may require a clear paper trail can help you avoid scrambling for documentation when closing day is getting close.

Why Changing Jobs for More Money Can Still Complicate a Home Purchase

Getting a new job with a higher salary sounds like good financial news, especially when you are preparing to buy a home. But if the change happens while you are applying for a mortgage, the timing can create additional questions. Mortgage qualification is not based solely on how much you earn. Lenders also evaluate the stability, history, and documentation of the income being used to qualify.

Higher Income Does Not Automatically Mean Easier Approval
A substantial raise can strengthen a buyer’s finances, but a new employment situation may need to be reviewed before that additional income can be used.

The type of compensation matters.

Moving from one salaried position to another may be relatively straightforward in some circumstances.

Changing from salary to commission, becoming self-employed, accepting variable hours, or moving into another compensation structure can require a different evaluation.

That distinction can matter even when the new position has greater earning potential.

Timing Can Create Extra Documentation
Employment and income are typically verified during the mortgage process.

If you change jobs after applying, the information originally provided on your application may no longer reflect your current employment.

Additional documentation may be required. Depending on the situation, that could include an offer letter, updated employment verification, or evidence that the new job has started.

Requirements vary based on the loan and circumstances.

A Career Change Can Be Different From a Job Change
Not all employment changes are viewed exactly the same way.

Moving to another employer while continuing similar work can present a different income history than changing industries, switching compensation structures, or starting your own business.

That does not mean buyers cannot make career moves while purchasing a home. It means the effect should be understood before making the change.

Talk Before You Give Notice
One of the simplest ways to avoid an unexpected mortgage complication is to communicate before changing employment.

If you are under contract or actively applying for financing, discuss the potential change with your mortgage professional before resigning from your current position.

Provide the details of the new job, including the anticipated start date and how you will be paid.

A better-paying opportunity can be an excellent career decision. The goal is not to avoid advancement simply because you are buying a house. It is to understand how the timing and structure of the change could affect your financing so that a positive career move does not create an unexpected problem before closing.