How Home Equity Builds Over Time

Home equity is the difference between what your home is worth and what you currently owe on it. It can become one of the most meaningful financial benefits of homeownership, but it usually develops gradually rather than all at once. Understanding how equity grows can help you track your progress and make more informed long-term financial decisions.

Mortgage Payments Reduce Your Balance

Each monthly mortgage payment generally includes an amount applied to principal and an amount applied to interest. The principal portion reduces what you owe, which increases your ownership stake in the property. Early in many loans, a larger share of the payment goes toward interest, but the principal portion often grows over time.

Home Value Changes Can Affect Equity

Equity may also increase when a home’s market value rises. Local demand, neighborhood improvements, employment growth, housing supply, and property condition can all influence value. Appreciation is never guaranteed, and values can move in either direction, so it is wise to view market growth as one part of the equity picture rather than the only strategy.

Improvements May Support Long-Term Value

Thoughtful maintenance and improvements can help protect a home’s condition and marketability. Not every project produces a dollar-for-dollar return, but addressing necessary repairs and choosing updates that appeal to a broad range of buyers may support value over time. Keep records of major projects for future reference.

Extra Principal Payments Can Accelerate Growth

Some homeowners choose to make additional principal payments when their budget allows. Even modest extra amounts may reduce the loan balance faster and lower total interest over the life of the loan. Before changing your payment strategy, confirm that additional funds will be applied to principal and consider whether maintaining savings should take priority.

Equity Is Not the Same as Available Cash

Although equity represents value you own, it is not money sitting in a savings account. Accessing it generally requires selling the home or qualifying for a loan secured by the property, which may involve interest, fees, and new monthly obligations. Treating equity as a long-term asset rather than automatic spending money can support healthier financial decisions.

Building equity is usually a long-term process created through regular mortgage payments, responsible property care, and changes in the home’s market value. Monitoring your loan balance and estimated property value can help you understand the progress you are making while keeping your broader financial goals in view.
How Mortgage Payments Change Over the Life of Your Loan

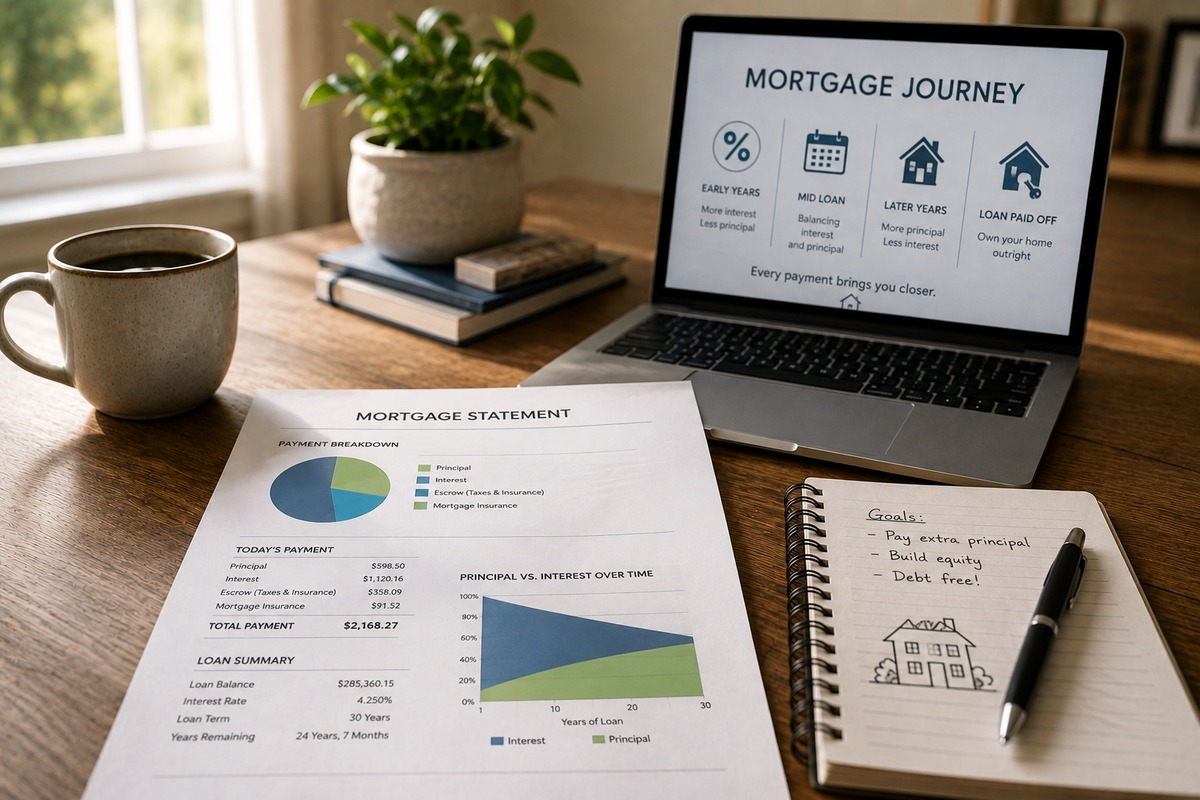
A mortgage payment may look consistent from month to month, but the way that payment works changes throughout the life of the loan. Understanding how principal, interest, escrow, and other costs evolve can help homeowners read statements more confidently and see the progress they are making over time.
Principal and Interest Shift Over Time

With a typical fixed-rate amortizing mortgage, the combined principal-and-interest payment remains the same. Early in the loan, a larger portion generally goes toward interest because the outstanding balance is higher. As the balance declines, more of each payment is applied to principal.

Escrow Can Change the Total Payment

Property taxes and homeowners insurance are separate from the fixed interest rate. If these expenses are collected through escrow, changes in tax bills, insurance premiums, or escrow shortages can increase or decrease the total monthly payment even when principal and interest remain stable.

Mortgage Insurance May Eventually End

Some borrowers pay mortgage insurance based on their loan type and down payment. Depending on the program and applicable rules, this cost may be eligible for cancellation after certain requirements are met, while other forms may remain for the life of the loan unless the mortgage is refinanced.

Extra Payments Affect the Timeline

Additional principal payments can reduce the outstanding balance and shorten the payoff period when applied correctly. They generally do not automatically change the scheduled monthly payment, but they may reduce the total interest paid over the life of the loan. Homeowners should confirm how their servicer applies extra funds.

Your mortgage is not static, even when the interest rate is fixed. The balance declines, the principal-and-interest mix changes, and taxes, insurance, or mortgage insurance may alter the total payment. Reviewing your statements regularly helps you understand these changes and track your progress toward owning the home outright.

Understanding Mortgage Servicing After Closing

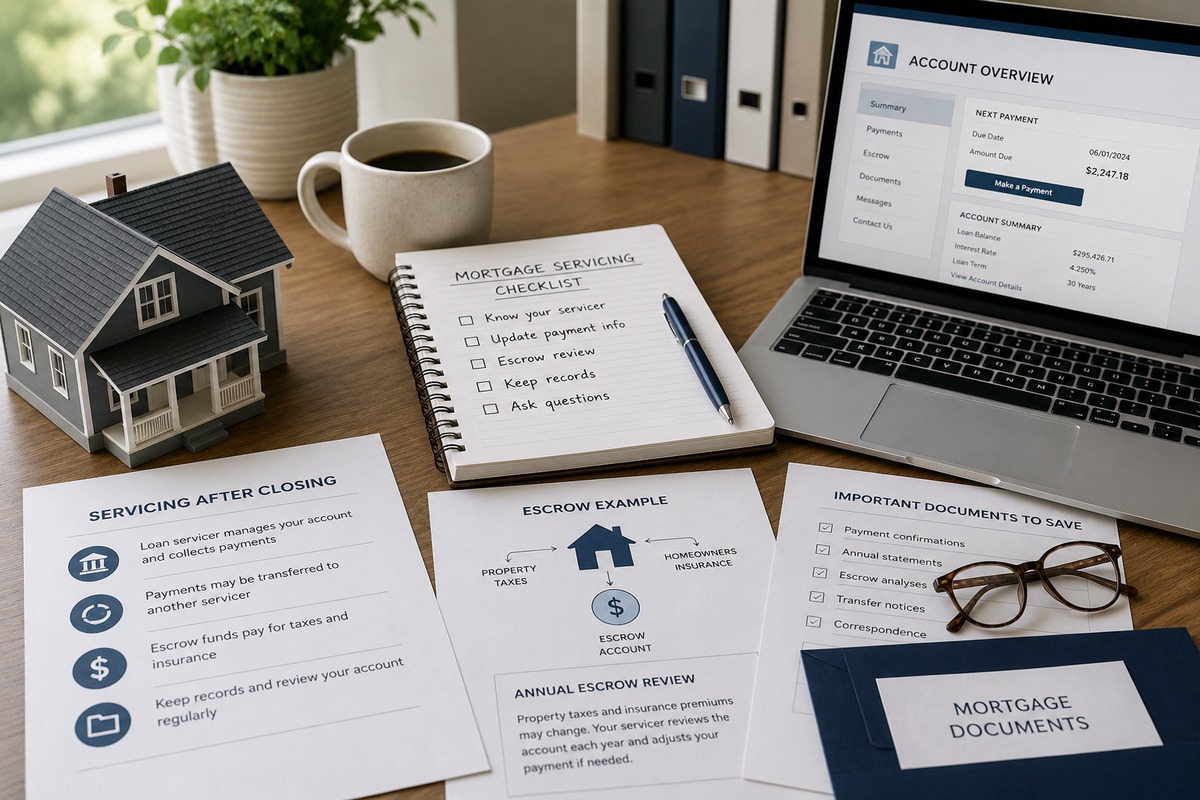
Closing day marks the end of the home-buying transaction, but it also begins the long-term process of managing your mortgage. After closing, a mortgage servicer becomes responsible for collecting payments, maintaining account records, managing escrow when applicable, and answering questions about your loan. Understanding the servicer’s role can help you avoid confusion and manage your mortgage with confidence.

Know the Difference Between a Lender and a Servicer

The company that originated your mortgage may not be the company that manages it afterward. Your lender provided the financing, while your servicer handles the day-to-day administration of the loan. In some cases they are the same company, but mortgage servicing rights may also be transferred.

Watch for Transfer Notices

If your loan is transferred, you should receive notices explaining when the change takes effect, where future payments should be sent, and how to contact the new servicer. A servicing transfer does not change your interest rate, loan balance, or other core terms. Review all notices carefully and update automatic payments when necessary.

Understand Escrow and Annual Reviews

If your payment includes an escrow account, the servicer collects funds for property taxes and homeowners insurance and pays those bills when due. The account is typically reviewed each year. Changes in taxes, insurance, or the escrow balance may cause your total monthly payment to increase or decrease.

Keep Records and Ask Questions

Save payment confirmations, annual statements, escrow analyses, and transfer notices. Review your account regularly and contact the servicer promptly if a payment is missing, a balance appears incorrect, or you receive an unfamiliar notice. Early communication can prevent small issues from becoming larger problems.

Mortgage servicing is the ongoing administrative side of your home loan. Knowing who manages your account, how transfers work, and how escrow affects your payment can make the years after closing much easier to navigate.