

How an Unfinished Basement Can Affect Your Mortgage Appraisal
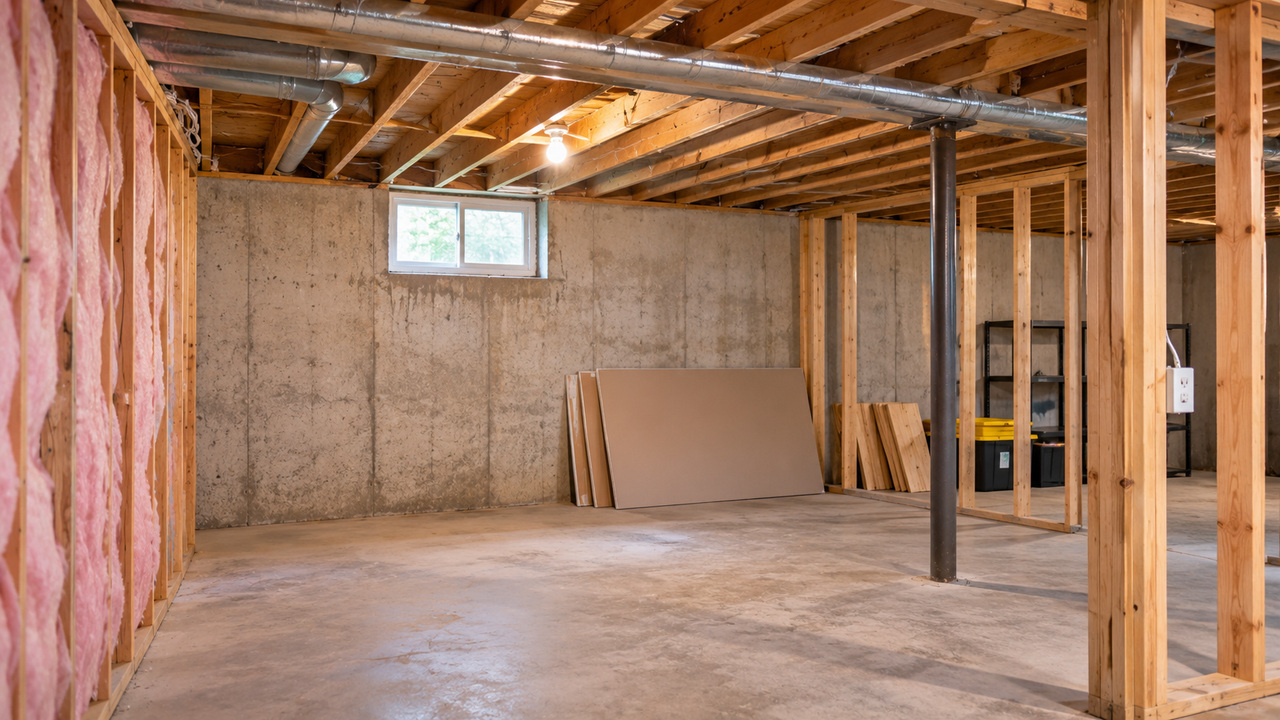 An unfinished basement can look like an opportunity. Buyers may imagine a future family room, guest space, home gym, or office. But when a home is being financed, the appraiser has to evaluate what exists today, not what the basement might become after a renovation. That distinction can affect the home’s reported living area, comparable sales, and ultimately the value used by the lender.
Finished and Unfinished Space Are Not the Same
A basement may be spacious, dry, and useful without qualifying as finished living area. Exposed framing, concrete floors, unfinished ceilings, and incomplete heating or electrical work can all affect how the space is classified. Even a beautifully finished basement may be reported separately from above-grade living area under commonly used appraisal measurement standards. Buyers should not assume that every usable square foot will be counted in the same category.
Why the Listing and Appraisal May Differ
Real estate listings sometimes describe total square footage in ways that include basement areas, while an appraisal may separate above-grade space from below-grade space. That does not necessarily mean either document is trying to mislead anyone. They may be applying different reporting conventions. The distinction matters when buyers compare a home with properties that have similar floor plans but different basement finishes.
Potential Does Not Equal Present Value
A seller may advertise an unfinished basement as space that could easily become an additional bedroom or rental suite. Those possibilities can be appealing, but they are not the same as an existing, legally permitted room. Adding bedrooms or living space may require permits, safe access, proper ceiling heights, emergency egress, and other improvements. An appraiser generally evaluates the current condition and market evidence rather than assigning full value to a project that has not been completed.
How This Can Affect Financing
A lender typically bases its loan-to-value calculation on the applicable appraised value, not simply the agreed purchase price. If the appraisal comes in below the contract price, the buyer may need to discuss options such as renegotiating, bringing additional funds, or reconsidering the purchase. An unfinished basement alone does not mean the home will appraise poorly. The outcome depends on the entire property and how comparable homes are selling.
Questions Worth Asking During a Showing
Find out whether the basement has experienced moisture intrusion, whether any past work was permitted, and which utilities are already installed. Ask for the listed square footage to be broken down between above-grade and below-grade areas. If you plan to finish the basement, obtain realistic estimates and investigate local permit requirements before treating the project as part of your financial plan.
An unfinished basement can be a valuable feature for the right buyer. Just remember that its future possibilities and its current appraised contribution are two different things. Understanding that difference helps you set a realistic budget and avoid surprises during mortgage approval.
 A home’s advertised square footage can influence which properties buyers tour, how they compare asking prices, and what they expect from an appraisal. But the number in a real estate listing is not always the same as the living area reported by a mortgage appraiser. Differences can occur even when nobody intended to provide misleading information. Understanding why can help buyers evaluate a home more accurately.