Why Your Mortgage Approval Can Change When the Home Has an Accessory Dwelling Unit
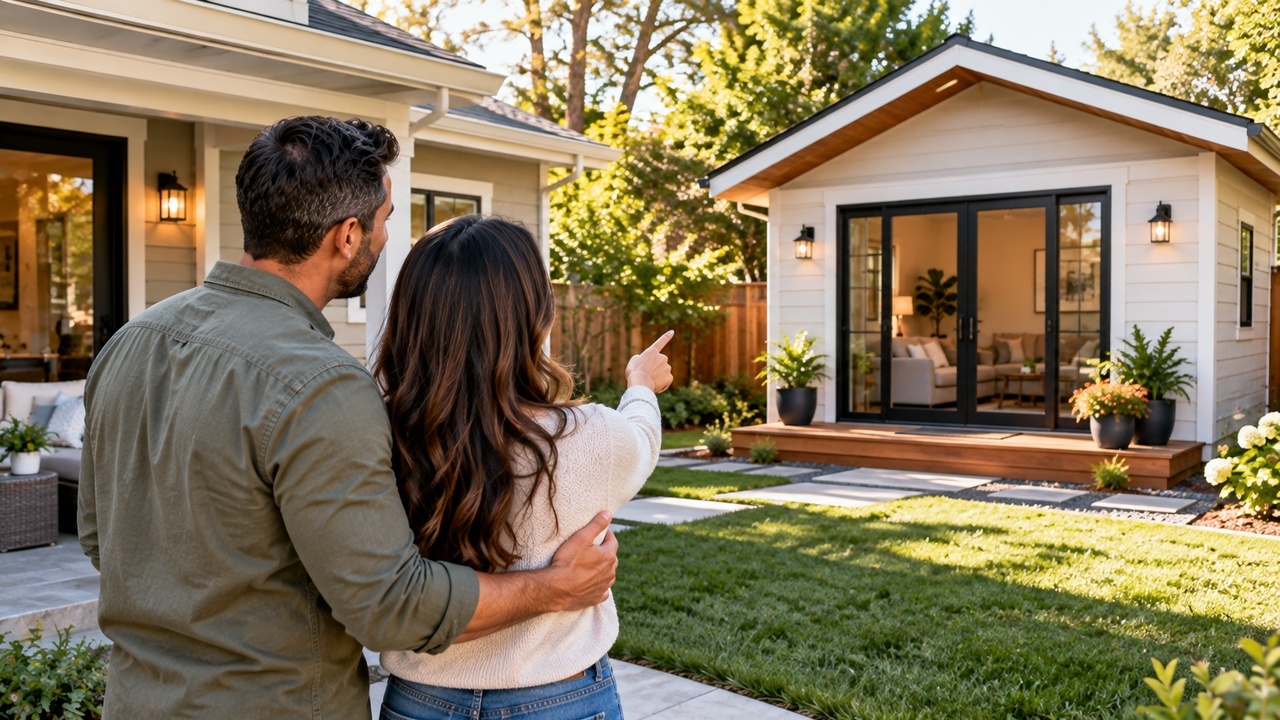
An accessory dwelling unit can make a property especially appealing. A detached guest house, converted garage, basement apartment, or backyard unit might provide space for relatives, a home office, or potential rental income.

But when you are financing the purchase, that additional living space can introduce questions that would not necessarily exist with a more traditional single-family home.

The Property Has to Be Evaluated Too
Mortgage approval is not based solely on the borrower’s income, credit, assets, and debts. The property securing the mortgage also has to meet applicable requirements.

When an ADU is present, the lender and appraiser may need to understand exactly what it is and how it relates to the primary residence.

Is it a separate structure? Does it have its own kitchen? Was an existing part of the property converted? These details can help determine how the property is evaluated.

Permits and Property Records May Matter
One important question is whether the additional living space was legally created and how it is reflected in available property records.

Buyers should not assume that a finished structure is automatically recognized as permitted living space simply because it looks professionally completed.

If something about the ADU is unclear, additional documentation or investigation may be needed.

Rental Income Is a Separate Question
Buyers sometimes see an ADU and immediately calculate how much rental income it could generate.

That potential income may be useful to your personal budget, but do not automatically assume it can be counted toward mortgage qualification.

Whether rental income from an ADU can be considered, and how much can be used, depends on the mortgage program, documentation, appraisal, occupancy plans, and other requirements.

Ask Before Building Your Budget Around It
If an ADU is an important reason you are considering a property, discuss it with your mortgage professional early. Explain how you intend to use the space and whether you are relying on anticipated rental income as part of your financial plan.

You may also want to ask your real estate professional about permits and available property information. An ADU can be an excellent feature, but it makes the property more than simply a house with an extra room.

Before assuming the additional space will strengthen your mortgage application or generate income immediately, understand how it will be treated in the transaction. That can help you evaluate the property based on what is actually possible rather than what you hope the extra space will provide.
Why the Money in Your Bank Account May Need a Paper Trail Before Closing

Having enough money in the bank is an important part of buying a home, but during the mortgage process, the amount in your account may not be the only consideration. In certain situations, lenders may also need to understand where funds came from. That can surprise buyers who assume that once money reaches their account, its history no longer matters.
Mortgage Funds May Need to Be Documented
During the mortgage process, buyers may provide bank or asset statements showing money available for the transaction.

If an account contains certain recent deposits that are not easily explained by the documentation already provided, additional information may be requested.

The purpose is not to question every dollar a buyer spends or receives. Mortgage guidelines may require lenders to verify certain funds being used in connection with the purchase.

Moving Money Can Make Things More Complicated
Buyers sometimes reorganize their finances before purchasing a home.

They may transfer money between checking and savings accounts, move funds from an investment account, deposit proceeds from selling personal property, or receive money from another person.

Even when the funds are legitimate, multiple transfers can create more documentation because the movement of money may need to be traced.

Keeping records can make that process considerably easier.

Gifts Have Their Own Requirements
Some buyers receive financial assistance from an eligible family member or another permitted source.

Depending on the mortgage program, gift funds may be allowed for some or all of the money needed for the transaction. However, there can be documentation requirements regarding the gift, donor, transfer, and source of funds.

Do not assume that depositing a large check into your account is all that is required.

Avoid Unnecessary Financial Shuffling
Before closing, simplicity can be valuable.

If you are considering moving a large amount of money, making an unusual deposit, changing bank accounts, or receiving funds from someone else, ask your mortgage professional what documentation may be needed.

Save statements, transaction confirmations, deposit records, and other relevant documentation rather than assuming you will never need them.

Money being available and money being properly documented are not always the same thing during a mortgage transaction.

You do not need to stop using your bank accounts normally while buying a home. But understanding that certain funds may require a clear paper trail can help you avoid scrambling for documentation when closing day is getting close.

Why Changing Jobs for More Money Can Still Complicate a Home Purchase

Getting a new job with a higher salary sounds like good financial news, especially when you are preparing to buy a home. But if the change happens while you are applying for a mortgage, the timing can create additional questions. Mortgage qualification is not based solely on how much you earn. Lenders also evaluate the stability, history, and documentation of the income being used to qualify.

Higher Income Does Not Automatically Mean Easier Approval
A substantial raise can strengthen a buyer’s finances, but a new employment situation may need to be reviewed before that additional income can be used.

The type of compensation matters.

Moving from one salaried position to another may be relatively straightforward in some circumstances.

Changing from salary to commission, becoming self-employed, accepting variable hours, or moving into another compensation structure can require a different evaluation.

That distinction can matter even when the new position has greater earning potential.

Timing Can Create Extra Documentation
Employment and income are typically verified during the mortgage process.

If you change jobs after applying, the information originally provided on your application may no longer reflect your current employment.

Additional documentation may be required. Depending on the situation, that could include an offer letter, updated employment verification, or evidence that the new job has started.

Requirements vary based on the loan and circumstances.

A Career Change Can Be Different From a Job Change
Not all employment changes are viewed exactly the same way.

Moving to another employer while continuing similar work can present a different income history than changing industries, switching compensation structures, or starting your own business.

That does not mean buyers cannot make career moves while purchasing a home. It means the effect should be understood before making the change.

Talk Before You Give Notice
One of the simplest ways to avoid an unexpected mortgage complication is to communicate before changing employment.

If you are under contract or actively applying for financing, discuss the potential change with your mortgage professional before resigning from your current position.

Provide the details of the new job, including the anticipated start date and how you will be paid.

A better-paying opportunity can be an excellent career decision. The goal is not to avoid advancement simply because you are buying a house. It is to understand how the timing and structure of the change could affect your financing so that a positive career move does not create an unexpected problem before closing.