What Happens to Your Mortgage When the Home Has an Unfinished Addition?
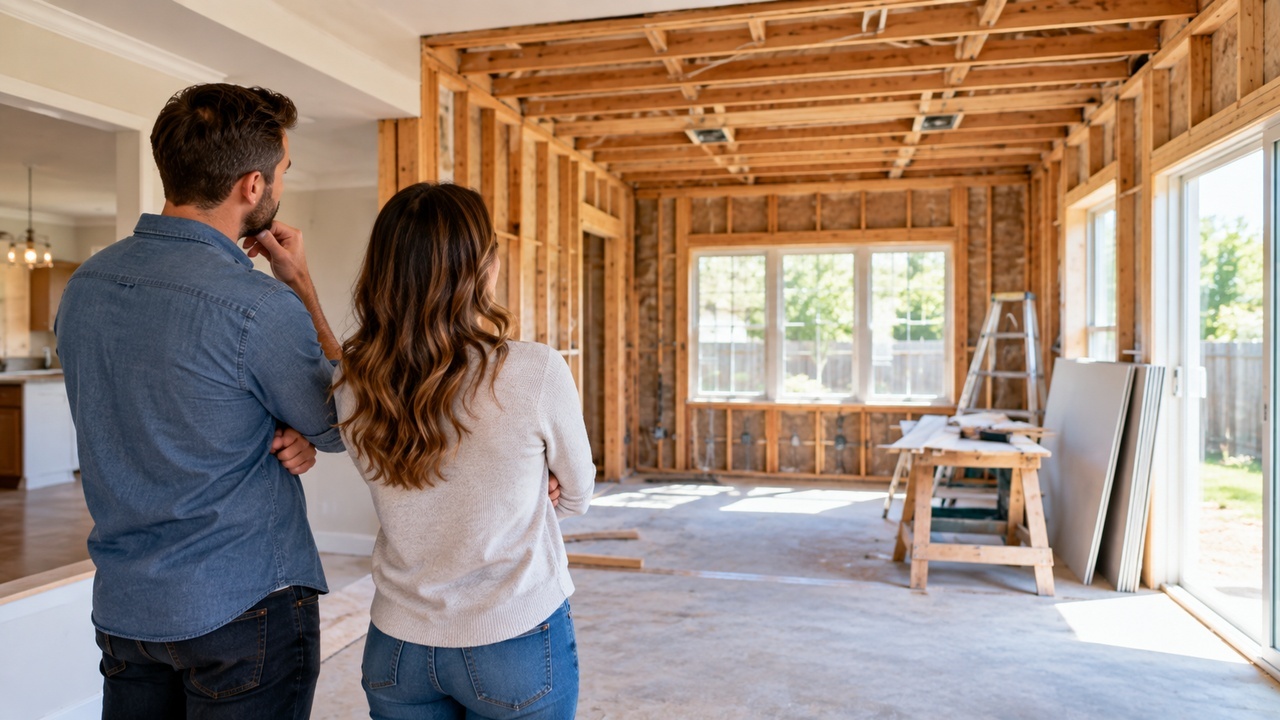
You find a home you love, but there is one unusual feature. Maybe the previous owner started adding a bedroom and never finished it. Perhaps a bathroom is partially remodeled, a garage conversion is incomplete, or a new section of the house is still visibly under construction.

Buyers may see opportunity in unfinished space, but a mortgage lender may need to evaluate the property as it exists today.

Financing Is Based on the Current Property
It is easy to walk through an unfinished addition and imagine what it could become.

The mortgage transaction, however, generally has to consider the property’s current condition rather than simply the buyer’s plans for completing it later.

The appraiser may need to identify unfinished areas and determine how they affect the property being valued.

Not All Unfinished Projects Are Equal
Missing cosmetic finishes are different from major incomplete construction.

A room awaiting paint or updated flooring presents a different situation than an addition with exposed framing, unfinished electrical work, missing plumbing fixtures, or other incomplete components.

The extent and type of unfinished work can influence what questions need to be answered.

Permits Can Become Part of the Conversation
An addition also raises another important question: Was the work properly permitted when required?

Buyers should understand what was added, who performed the work, and what information is available through the seller or applicable local records.

An attractive partially completed space should not automatically be assumed to be recognized living area.

Do Not Assume You Can Finish It After Closing
Buyers sometimes approach an unfinished project with a simple plan: purchase the property now and complete everything later.

That may ultimately be possible, but it should not be assumed before the financing has been reviewed.

Depending on the property condition and mortgage program, incomplete work could require additional evaluation or affect available financing options.

If you are seriously considering a home with an unfinished addition, show the details to your mortgage professional as early as possible. Photos, listing information, disclosures, and information about the work can help start the conversation.

A half-finished room may look like an opportunity to create exactly what you want.

Just remember that before you can finish the project as the homeowner, you first have to successfully purchase the property in its present condition.
What Happens When Your Closing Date Gets Pushed Back?

You scheduled the movers, arranged time off work, started packing, and expected to receive the keys on Friday. Then you learn that closing needs to be delayed. Even a short change in the closing date can affect more than moving day, which is why buyers should understand what may need attention when the timeline changes.
The Mortgage Timeline May Need Attention
A mortgage transaction contains several items tied to specific time periods.

Depending on the circumstances, a closing delay could affect documents, verifications, or other time-sensitive portions of the loan process.

One important example is an interest rate lock. Rate locks generally apply for a defined period. If closing moves beyond that period, buyers should find out whether an extension is necessary and whether any cost or other conditions are associated with it.

Your Cash-to-Close Numbers Can Change
Changing the closing date can sometimes change certain amounts shown in the transaction.

Prepaid interest is one example because the amount can depend partly on the date the loan closes. Other prorated items associated with the transaction may also need to be recalculated.

That means buyers should review updated closing information rather than assuming every number will remain exactly the same.

The Moving Plan May Need to Move Too
The financial side is only part of the inconvenience.

Movers, utility transfers, deliveries, time off work, temporary lodging, and the end of a lease may all have been scheduled around the original closing date.

Whenever possible, avoid creating a schedule that leaves absolutely no flexibility between closing and another major deadline. A small cushion can be extremely valuable if the transaction shifts by a day or two.

Do Not Assume You Have the House Until Closing Is Complete
Buyers can understandably become excited once the closing date is placed on the calendar, but it is important to remember that the transaction still has steps to complete. Avoid making irreversible plans based solely on an anticipated closing date.

If a delay occurs, ask what caused it, what remains outstanding, and whether anything is needed from you. Also confirm whether the change affects your mortgage, funds required, rate lock, insurance, or other arrangements.

Most buyers hope for a perfectly predictable closing. Real estate transactions, however, involve multiple parties and moving pieces. Planning for a little flexibility can make an unexpected delay far less disruptive and help keep the focus where it belongs: successfully completing the purchase and getting the keys.

Why the Money in Your Bank Account May Need a Paper Trail Before Closing

Having enough money in the bank is an important part of buying a home, but during the mortgage process, the amount in your account may not be the only consideration. In certain situations, lenders may also need to understand where funds came from. That can surprise buyers who assume that once money reaches their account, its history no longer matters.

Mortgage Funds May Need to Be Documented
During the mortgage process, buyers may provide bank or asset statements showing money available for the transaction.

If an account contains certain recent deposits that are not easily explained by the documentation already provided, additional information may be requested.

The purpose is not to question every dollar a buyer spends or receives. Mortgage guidelines may require lenders to verify certain funds being used in connection with the purchase.

Moving Money Can Make Things More Complicated
Buyers sometimes reorganize their finances before purchasing a home.

They may transfer money between checking and savings accounts, move funds from an investment account, deposit proceeds from selling personal property, or receive money from another person.

Even when the funds are legitimate, multiple transfers can create more documentation because the movement of money may need to be traced.

Keeping records can make that process considerably easier.

Gifts Have Their Own Requirements
Some buyers receive financial assistance from an eligible family member or another permitted source.

Depending on the mortgage program, gift funds may be allowed for some or all of the money needed for the transaction. However, there can be documentation requirements regarding the gift, donor, transfer, and source of funds.

Do not assume that depositing a large check into your account is all that is required.

Avoid Unnecessary Financial Shuffling
Before closing, simplicity can be valuable.

If you are considering moving a large amount of money, making an unusual deposit, changing bank accounts, or receiving funds from someone else, ask your mortgage professional what documentation may be needed.

Save statements, transaction confirmations, deposit records, and other relevant documentation rather than assuming you will never need them.

Money being available and money being properly documented are not always the same thing during a mortgage transaction.

You do not need to stop using your bank accounts normally while buying a home. But understanding that certain funds may require a clear paper trail can help you avoid scrambling for documentation when closing day is getting close.