Can You Get a Mortgage on a Home That Has Been Moved From Another Location?
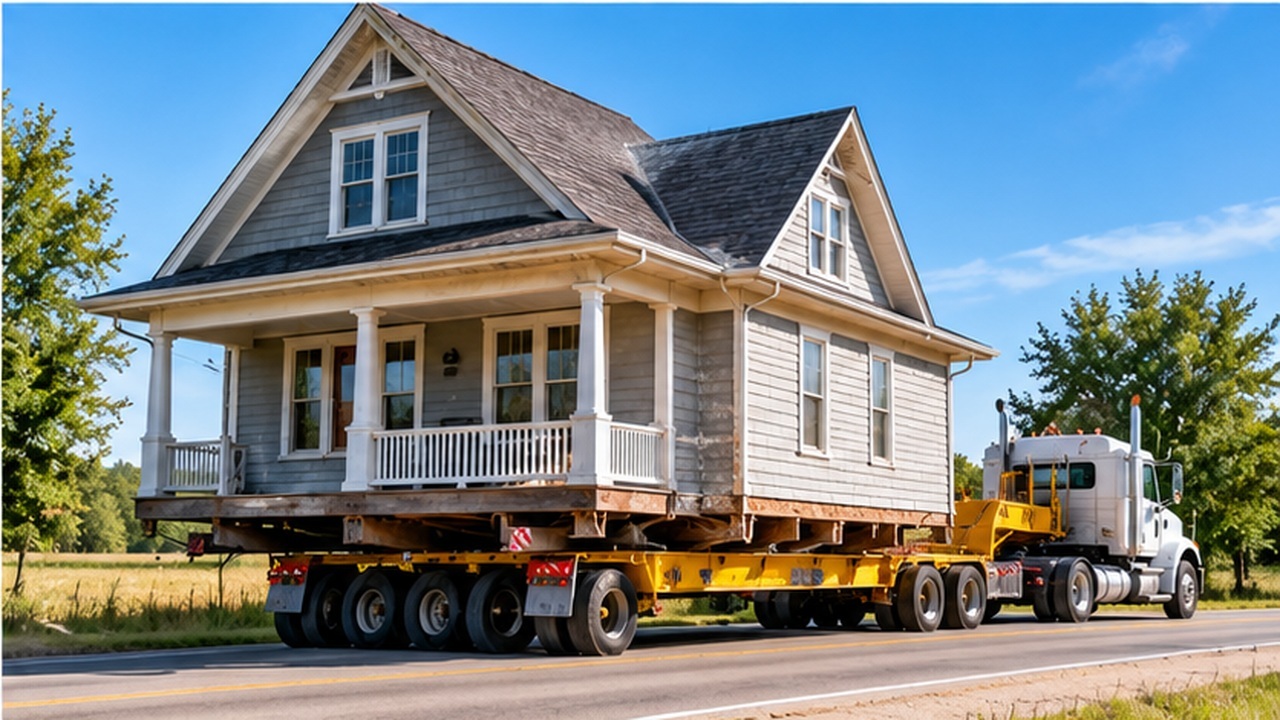
Most buyers assume that the home they are purchasing has always been located on its current property. However, some houses have been physically relocated from one location to another.

Whether a historic home was preserved by moving it or an existing structure was transported to a new lot, the property’s relocation history can create unique questions during the mortgage process.

Why Would Someone Move an Entire House?
Moving an existing home is more common than many people realize, particularly in areas where older houses are preserved or land is being redeveloped.

Instead of demolishing a structure, an owner may hire specialized contractors to lift the house, transport it, and place it on a new foundation.

In other situations, a house may be relocated to make room for construction or to preserve a building with historical significance.

Although the home may look completely normal once the project is finished, its relocation history can still be relevant when applying for financing.

The Foundation Can Be an Important Factor
When a home is moved, it generally must be placed on a suitable foundation at its new location.

Mortgage lenders and appraisers may need to evaluate whether the foundation and structure meet applicable requirements.

Depending on the property and loan program, additional documentation may be requested regarding the foundation, building permits, inspections, and completed relocation work.

Buyers should not assume that a home is automatically eligible for financing simply because it has been occupied since the move.

Property Records May Need Clarification
A relocated house may have a construction history that differs from the records associated with its current lot.

For example, the house may have been originally built decades earlier but moved to its present location much more recently.

The lender or appraiser may need to understand the difference between the original construction date and the date of relocation.

Permit records, certificates of occupancy, and other local documentation may help establish that the relocation was completed appropriately.

Missing or inconsistent information could lead to additional questions before the mortgage is approved.

Appraising a Relocated Home
Determining market value may also require careful consideration.

The appraiser evaluates the property in its current location and condition, rather than relying solely on what the structure may have been worth before it was moved.

Factors such as the foundation, overall condition, neighborhood, available comparable sales, and quality of completed work can influence the valuation.

A relocated house is not automatically worth less, but unusual property characteristics may require additional analysis.

What Buyers Should Do Before Applying
Buyers interested in a relocated home should ask when the move occurred, who performed the work, and what documentation is available.

They should also discuss the home’s history with their mortgage professional before committing to a financing timeline.

For buyers who appreciate unique or historic properties, a relocated home can offer considerable charm. The key is understanding the property’s history and confirming that its current condition and documentation support the intended mortgage financing.
Why Buying a Home From a Family Member Can Make the Mortgage More Complicated

Buying a home from a parent, grandparent, sibling, or another relative may seem easier than purchasing from a stranger. You already know the seller, may know the property’s history, and might even agree on a price without extensive negotiations.
But the family relationship can introduce mortgage considerations that are different from those in a typical purchase between unrelated parties.

The Relationship Matters
A transaction between people with an existing relationship may be considered differently from a traditional arm’s-length sale.

That does not mean family transactions are prohibited. It means the lender may need to understand the relationship between the buyer and seller and review the structure of the transaction accordingly.

Being clear about the relationship from the beginning is important.

A Gift of Equity May Be Possible
One feature sometimes associated with family transactions is a gift of equity.

Instead of giving the buyer cash for a down payment, an eligible family member selling the property may be able to provide a portion of the home’s equity as a gift within applicable mortgage guidelines.

How a gift of equity can be used depends on the mortgage program and transaction, and documentation requirements can apply.

Buyers should discuss the proposed structure before agreeing on final numbers.

The Appraisal Still Matters
A family member may be willing to sell a property for less than they believe it is worth, but the agreed price does not eliminate the appraisal process when an appraisal is required.

The property still needs to be evaluated independently for the mortgage transaction.

That can become particularly important when a gift of equity or below-market sale is involved.

Treat It Like a Financial Transaction
Family relationships can make buyers and sellers more comfortable relying on verbal agreements.

A home purchase is too significant for assumptions.

Make sure the purchase price, credits, responsibilities, timelines, and other terms are properly documented through the appropriate transaction paperwork.

Buying a relative’s home can create an opportunity that would never reach the open market. It can also allow a property with family history to remain within the family.

The key is to remember that familiarity between buyer and seller does not eliminate the mortgage process.

Discuss the family relationship, proposed purchase price, and any planned gift of equity with your mortgage and real estate professionals early so the transaction can be structured correctly from the beginning.

What Happens to Your Mortgage When the Home Has an Unfinished Addition?

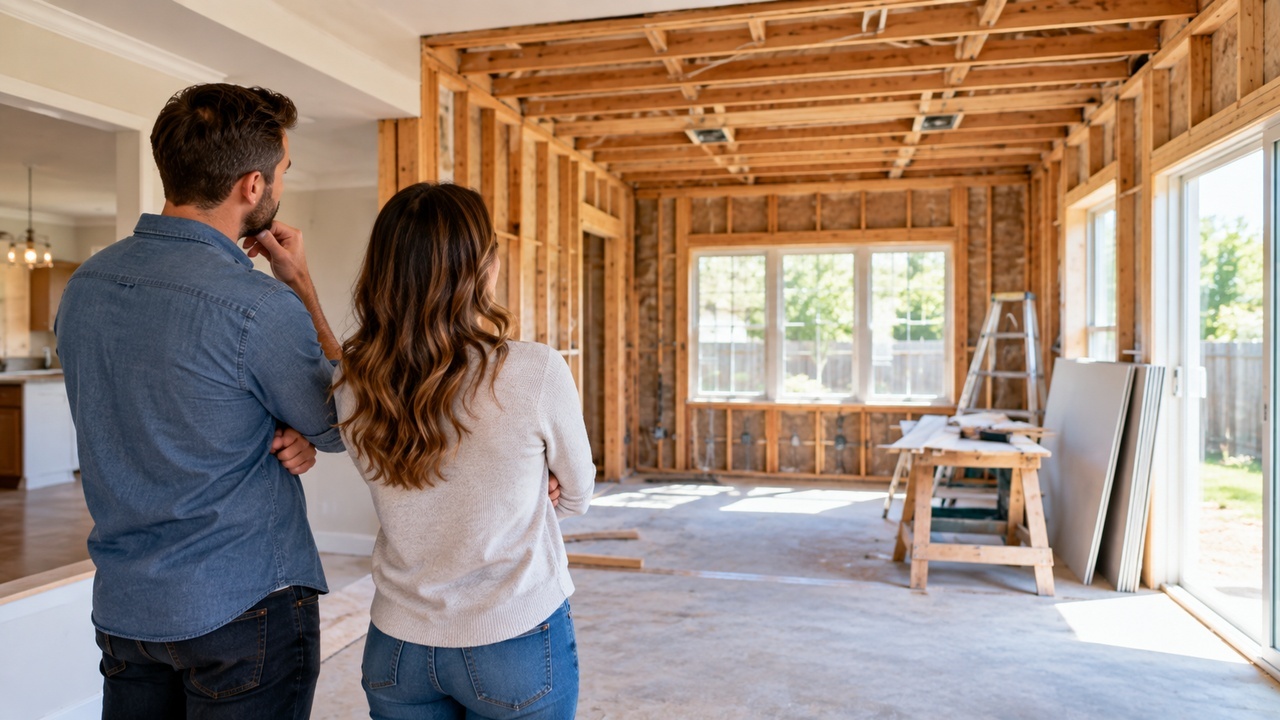
You find a home you love, but there is one unusual feature. Maybe the previous owner started adding a bedroom and never finished it. Perhaps a bathroom is partially remodeled, a garage conversion is incomplete, or a new section of the house is still visibly under construction.

Buyers may see opportunity in unfinished space, but a mortgage lender may need to evaluate the property as it exists today.

Financing Is Based on the Current Property
It is easy to walk through an unfinished addition and imagine what it could become.

The mortgage transaction, however, generally has to consider the property’s current condition rather than simply the buyer’s plans for completing it later.

The appraiser may need to identify unfinished areas and determine how they affect the property being valued.

Not All Unfinished Projects Are Equal
Missing cosmetic finishes are different from major incomplete construction.

A room awaiting paint or updated flooring presents a different situation than an addition with exposed framing, unfinished electrical work, missing plumbing fixtures, or other incomplete components.

The extent and type of unfinished work can influence what questions need to be answered.

Permits Can Become Part of the Conversation
An addition also raises another important question: Was the work properly permitted when required?

Buyers should understand what was added, who performed the work, and what information is available through the seller or applicable local records.

An attractive partially completed space should not automatically be assumed to be recognized living area.

Do Not Assume You Can Finish It After Closing
Buyers sometimes approach an unfinished project with a simple plan: purchase the property now and complete everything later.

That may ultimately be possible, but it should not be assumed before the financing has been reviewed.

Depending on the property condition and mortgage program, incomplete work could require additional evaluation or affect available financing options.

If you are seriously considering a home with an unfinished addition, show the details to your mortgage professional as early as possible. Photos, listing information, disclosures, and information about the work can help start the conversation.

A half-finished room may look like an opportunity to create exactly what you want.

Just remember that before you can finish the project as the homeowner, you first have to successfully purchase the property in its present condition.