Can a Home-Based Business Affect Your Mortgage Approval?
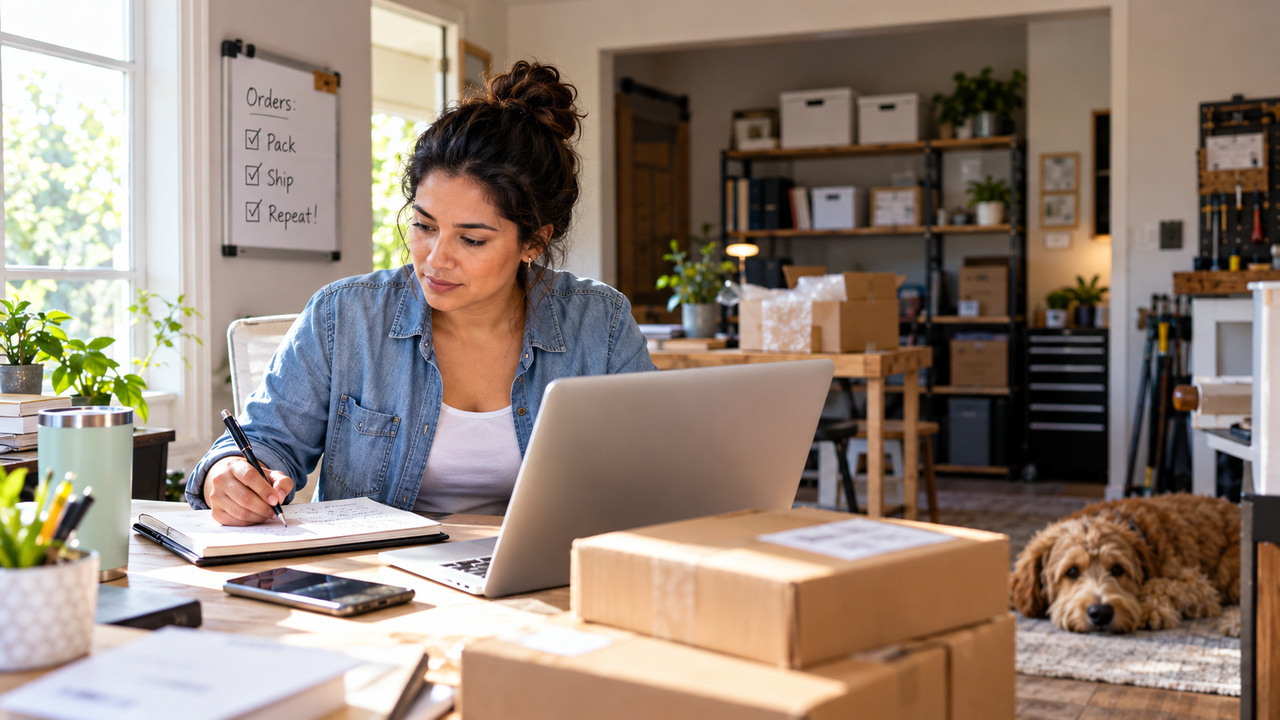
A home office, a small workshop, or a room used to meet clients may seem like a normal part of modern homeownership. But when you apply for a mortgage, the way a property is used can matter just as much as how it looks. A home-based business does not automatically prevent financing. The questions usually involve whether the property remains primarily residential, whether its use is permitted, and whether the lender can comfortably evaluate it as a home.

Residential Use Comes First

Most standard residential mortgage programs are designed for properties used primarily as residences. Working remotely from a spare bedroom is generally different from operating a storefront, manufacturing facility, or business that occupies most of the building. Lenders may look at the amount of space devoted to business activity, whether customers visit regularly, and whether the property’s layout still resembles a typical residence.

A detached workshop or converted garage may raise additional questions. For example, a garage with a workbench is different from a building outfitted as a full commercial operation. The distinction is not simply whether someone earns money there. It is how the business use affects the property’s character and marketability.

Zoning and Permits Matter

Local rules can determine which businesses are allowed in residential neighborhoods. Some communities permit low-impact home occupations but restrict signs, employee parking, customer traffic, noise, or storage. A business that violates local zoning requirements may create concerns for a lender or appraiser.

Changes to the property can matter, too. If a homeowner removed a kitchen, built a separate entrance for clients, or converted living space into specialized commercial rooms, the lender may ask whether those changes were properly permitted and whether the property can readily function as a residence.

What the Appraiser Evaluates

An appraiser considers the property as it exists, including its layout, condition, and appeal to typical buyers in the area. Unusual business improvements do not necessarily add the same value that they cost to install. Highly specialized features may even make comparable sales harder to identify.

The appraiser may also note whether the business area can be converted back to ordinary residential use. A flexible home office often presents fewer valuation questions than permanent alterations designed for a narrow commercial purpose.

Income Is a Separate Question

If you own the business, your self-employment income may require additional documentation. That is a borrower qualification issue, separate from whether the property itself is acceptable collateral. A lender may review tax returns, business financials, or other records to evaluate qualifying income, depending on the loan program.

Questions to Ask Before You Buy

Ask how the property is zoned, whether business-related improvements have permits, and whether any homeowners association limits commercial activity. Share the intended use with your mortgage professional early, especially if the business requires dedicated facilities or frequent visitors.

A home-based business and a residential mortgage can often coexist. The safest approach is to confirm that the property remains suitable for residential financing before relying on an assumed approval timeline.
Understanding the Financial Power of Mortgage Points

In the world of home financing, mortgage points are a powerful yet often misunderstood tool that can significantly impact your long-term financial outlook. Whether you’re purchasing a home or refinancing, understanding how these points work can help you make more informed decisions that align with your financial goals.
What Are Mortgage Points?

Mortgage points, also known as discount points, are a way for borrowers to reduce the interest rate on their loan by making an upfront payment. Each point typically costs 1% of the total loan amount and can reduce your interest rate by around 0.25%. The idea is simple: pay more upfront to save on interest over the life of the loan.

Types of Mortgage Points: Discount vs. Origination

There are two main types of points to be aware of:

  1. Discount Points
    These points allow borrowers to lower their interest rate by making an upfront payment. The more discount points you buy, the lower your interest rate, which can lead to significant savings on your monthly mortgage payment. This option is most beneficial if you plan to stay in your home for a long period, as the upfront cost of purchasing points will be recouped through the interest savings over time.
  2. Origination Points
    Origination points, on the other hand, are fees paid to the lender for processing the loan. These points don’t reduce your interest rate but are part of the overall cost of obtaining the loan.

When Do Mortgage Points Make Sense?

Deciding whether to purchase mortgage points depends on several factors. Here are a few key considerations:

  • Long-Term Homeownership
    If you plan to stay in your home for several years, buying discount points can make financial sense. The longer you stay, the more you benefit from the reduced interest rate. For example, if you’re in your home for 10 or more years, the savings from a lower rate can easily outweigh the initial cost of the points.
  • Upfront Investment
    Purchasing mortgage points requires an upfront investment. It’s essential to evaluate whether you have the funds available to cover these costs. If you can comfortably afford the upfront expense, the savings over the life of the loan may be worth it.
  • Interest Rate Environment
    The current interest rate landscape plays a role in determining whether buying points is a good move. In a low-interest-rate market, purchasing points to further lower your rate may offer significant savings. However, if rates are already low, the additional reduction may not provide as much benefit.
  • Loan Comparison
    It’s important to compare offers from different lenders. Some lenders may offer more favorable terms on points, making it easier to achieve the desired interest rate reduction. By analyzing multiple loan offers, you can determine the best combination of points and interest rates for your situation

By understanding the role of mortgage points, you can tailor your financing strategy to suit your financial goals. Whether you’re considering purchasing or refinancing, the decision to buy points should align with your long-term homeownership plans, your ability to invest upfront, and the current interest rate market. By taking these factors into account, you’ll be better equipped to make informed decisions that pave the way to a secure financial future.

Mortgage Protection and Insurance for Your Home Loan

When buying a home, mortgage insurance can be an important but often misunderstood component of your loan. It is designed to protect lenders from the risk of borrower default, but it can also impact your monthly payments and overall loan cost. Knowing the types of mortgage insurance, when it is required, and how to manage it can help you make informed decisions and potentially save money over the life of your loan.

Types of Mortgage Insurance
There are several types of mortgage insurance that borrowers may encounter. Private mortgage insurance, or PMI, is typically required for conventional loans when the down payment is less than twenty percent. Government-backed loans, such as FHA loans, have their own insurance premiums, which may include both upfront and monthly payments. Understanding the differences can help you anticipate costs and choose the right loan product.

When Mortgage Insurance Is Required
Lenders usually require mortgage insurance when they consider the loan risk to be higher. This often occurs with smaller down payments, lower credit scores, or certain loan programs. While it protects the lender, it does not provide direct benefits to the homeowner. However, mortgage insurance can make homeownership possible for borrowers who cannot afford a large down payment.

How to Minimize or Remove Mortgage Insurance
There are several strategies to reduce or eliminate mortgage insurance over time. Increasing your down payment can prevent PMI from being required initially. For existing loans, lenders may allow cancellation of PMI once you reach twenty percent equity in the home. Refinancing can also be a way to remove mortgage insurance, depending on current rates and property value.

Benefits and Considerations
While mortgage insurance increases monthly payments, it can enable homeownership sooner than saving for a larger down payment. Borrowers should weigh the cost against the benefit of buying a home sooner and consider how long they plan to stay in the property. Strategic planning and discussion with a mortgage professional can help ensure that mortgage insurance works for your financial goals.

Understanding mortgage insurance is a key step in managing your home financing effectively. By knowing when it is required, how it works, and strategies to reduce costs, borrowers can approach homeownership with confidence and financial clarity.