Personal CA-DRE #01455710 · NMLS #256707  |  Company CA-DRE #02075839 · NMLS #1777223

Blog

What’s Ahead For Mortgage Rates This Week – November 16th, 2026
The inflation reports have been released, and the data has largely come in within expectations, with the Producer Price Index (PPI) coming in slightly lower than expected. However, when looking at the acceleration of inflation over the latter half of the year, it has been nearly twice as high as it was at the start of the year. It is unlikely that interest rates will change from their current levels, and there is a greater likelihood that we could see another rate increase. 

Since the war in Iran, the Producer Price Index has seen a larger increase in inflation. Even when looking at core inflation rates, which exclude food and energy prices, core PPI remains at a very high 5%. Meanwhile, headline producer prices have risen 6.5% over the past 12 months, indicating that inflationary pressures remain elevated.

Consumer Price Index
The annual inflation rate in the US rose to 4.2% in May 2026, marking its highest level since April 2023, from 3.8% in April and in line with market expectations. This represents the third consecutive monthly acceleration in headline inflation, with energy costs jumping 23.5% (vs 17.9% in April), due to the energy shock triggered by the conflict with Iran. Gasoline prices soared 40.5%, after a 28.4% gain. Fuel oil also increased 58.9% (vs 54.3%). In addition, inflation accelerated once again for shelter (3.4% vs 3.3%) and food (3.1% vs 2.3%). 

Producer Price Index
U.S. producer prices rose 2.7% year-on-year in March 2025, easing from a 3.2% increase in February and coming in below market expectations of a 3.3% rise. This marked the smallest annual gain in producer prices since September. On a monthly basis, prices fell 0.4%, following an upwardly revised 0.1% increase in February and missing forecasts for a 0.2% gain, largely driven by a sharp drop in energy costs. Despite the pullback, producer prices are expected to trend higher in the coming months due to the impact of new tariffs.

Primary Mortgage Market Survey Index

  • 15-Year FRM rates saw a decrease of -0.12%, bringing the current rate to 6.45%.
  • 30-Year FRM rates saw a decrease of -0.07%, bringing the current rate to 7.11%.

MND Rate Index

  • 30-Year FHA rates saw an increase of 0.23%, with the current rate at 7.05%.
  • 30-Year VA rates saw an increase of 0.23%, with the current rate at 7.07%.

Jobless Claims
Initial Claims were reported to be 200,000 compared to the expected claims of 195,000. The previous week landed at 191,000.

What’s Ahead
FOMC Minutes, Consumer Sentiment and Retail Sales reports are leading the way next week.
How a Solar Panel Lease Can Complicate a Home Purchase

Solar panels can be an appealing feature when you are shopping for a home. They may help offset electricity costs, and many buyers like the idea of producing energy on-site. But there is an important difference between buying a house with solar panels that are owned outright and buying one with panels covered by a lease or another financing agreement.
That difference can matter during mortgage approval and long after closing.

Start With Who Owns the Panels

Some homeowners purchase their solar systems outright. Others finance the equipment with a loan, sign a solar lease, or enter into a power purchase agreement under which they pay for the electricity generated. These arrangements can create different payment obligations and responsibilities for maintenance, repairs, and equipment removal.

Do not assume the panels are included in the home sale simply because they are attached to the roof. Ask the seller for the complete solar agreement and any related loan documents before you make a final decision.

Why Your Lender Needs the Details

A lender may need to determine whether the solar equipment is owned, leased, or subject to a lien or other recorded interest. The agreement can affect how the property is valued, what obligations transfer to the buyer, and whether the financing arrangement meets the loan program’s requirements.

If the buyer must assume a monthly solar payment, that obligation may also need to be considered during mortgage qualification, depending on the loan type and agreement. A solar company may require its own approval before a lease or contract can be transferred. These steps can take time, so discovering the arrangement shortly before closing is rarely ideal.

Look Beyond the Monthly Payment

Ask how long the agreement lasts, whether payments increase over time, who maintains the panels, and what happens if the roof needs replacement. Find out whether the contract can be transferred to a new owner, bought out, or terminated, and what each option costs. Review whether the seller is responsible for paying off any balance before closing.

You should also compare recent utility bills with the solar payments to understand the home’s actual energy expenses. Savings advertised in a listing may not match your future usage or the terms you will inherit.

Get the Documents Early

Share the solar paperwork with your lender, real estate agent, and title or closing professional as soon as possible. If you have questions about contract obligations, consider seeking advice from an appropriate legal professional. A solar system does not automatically make a home difficult to finance, but an unclear agreement can create delays.

The goal is simple: know exactly what comes with the home, what you will owe, and what your mortgage lender needs before you commit.

Why an Unpermitted Garage Conversion Can Affect Your Mortgage

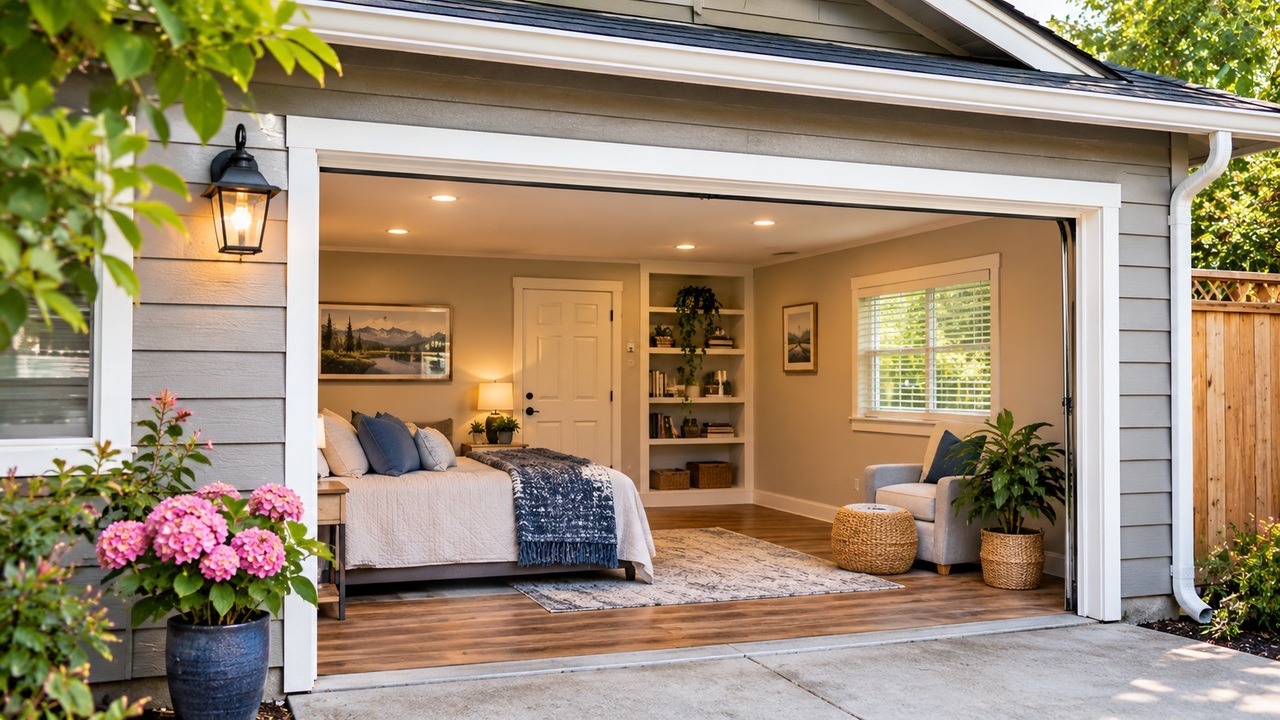
A converted garage can make a house feel more useful. It might serve as a bedroom, home office, playroom, or guest space. But before you count that room as part of the home’s living area, there is a question worth asking: Was the conversion properly permitted and approved?

For mortgage purposes, the answer can influence how the property is described, appraised, and reviewed. A room that looks finished is not necessarily recognized as legal living space.

Permits and Living Area Are Different Questions

Local building departments set rules for construction, electrical work, heating, ventilation, windows, and changes in a room’s use. A garage conversion may need permits and inspections, especially when the work changes structural elements or adds plumbing. The rules depend on the location and the scope of the project.

An appraiser may also need to determine whether the converted area meets applicable standards for inclusion in the home’s finished living area. A converted garage may be treated differently from the original house, even if it has attractive flooring and painted walls. It is important not to assume that every finished square foot shown in a listing will be included in the appraisal the same way.

How It Can Affect Financing

If the home’s advertised bedroom count or square footage depends on an unpermitted conversion, the appraised value may not match the asking price. A lender may also have questions about safety, marketability, or whether additional documentation or repairs are necessary. In some situations, the conversion may not prevent financing. In others, unresolved issues could delay approval or change the loan options available.

The details matter, and requirements vary by lender and loan program. That is why buyers should avoid relying on a blanket rule about whether unpermitted work is acceptable.

Questions to Ask Before Making an Offer

Ask the seller when the garage was converted and whether permits were obtained. Request copies of permits, inspection signoffs, and any certificates or records required locally. Compare the listing description with public property records, while remembering that records can sometimes be incomplete or outdated. A qualified home inspector can help identify visible concerns, but only the appropriate local authority can confirm permit status.

Talk with your lender early if the converted space is a major reason you want the property. Ask how it might be treated in the appraisal and whether documentation could be required. Your real estate agent can also help you evaluate the home based on its verified features rather than marketing descriptions alone.

A garage conversion may be a wonderful addition. Understanding how it was completed can help prevent a surprise when financing and appraisal reviews begin.