Can You Finance a Home That Has a Second House on the Property?
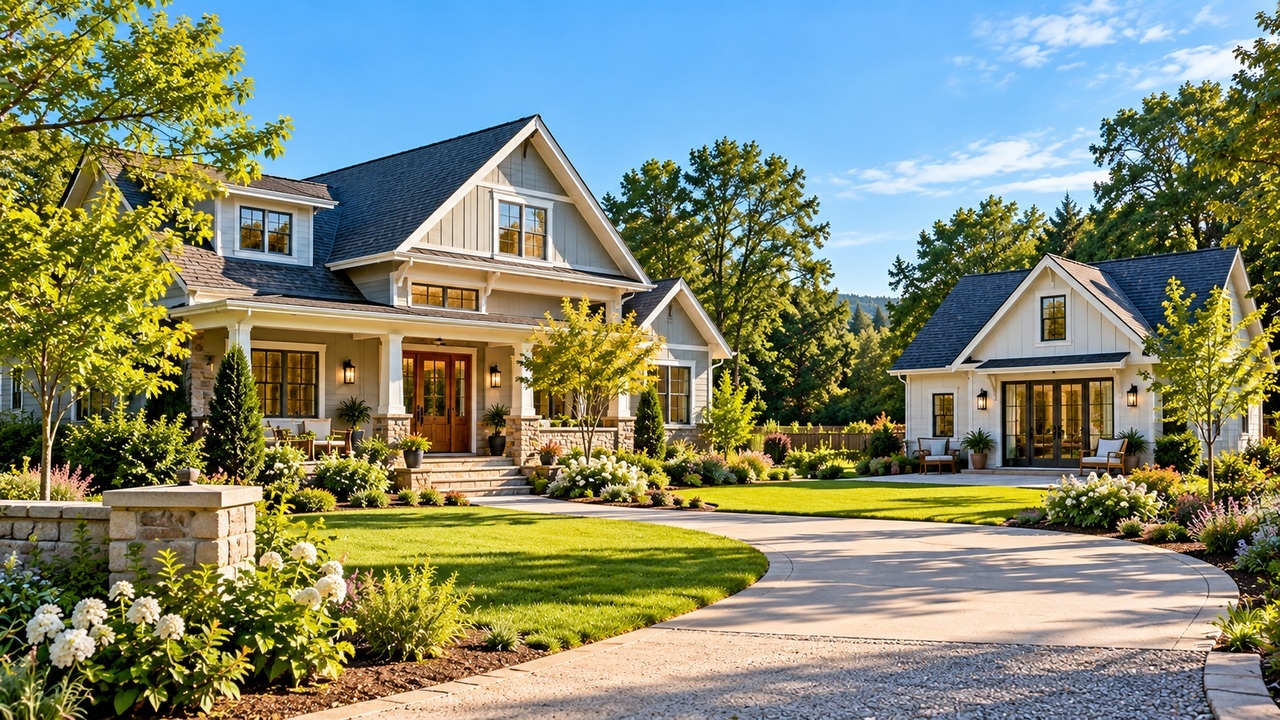
Finding a property with two houses can feel like discovering a bonus. The smaller home might provide space for relatives, visiting friends, or future rental income. Before making plans, however, buyers should understand that financing a property with two residences may be different from financing a typical single-family home.

Start With How the Property Is Classified

A detached second house is not always treated the same way as an accessory dwelling unit, commonly called an ADU. Local zoning rules, permits, separate utility connections, and the property’s legal description can influence how the additional structure is classified.

Some properties have a main residence and a smaller permitted ADU. Others contain two independent houses, perhaps built decades apart. A lender needs to know what is actually being purchased rather than relying on a listing description that calls the second structure a guesthouse.

Mortgage Programs Have Different Rules

Loan programs can have different standards for eligible property types, number of dwelling units, and acceptable accessory structures. A property that qualifies under one program may require a different approach under another.

The lender may review whether the homes are on the same legal parcel, whether both can be occupied independently, and whether the second structure has appropriate permits. If the property is considered a two-unit residence rather than a single-family home with an ADU, financing terms and documentation may change.

Appraisal Questions Matter, Too

The appraiser must evaluate the property in its current condition and determine how the additional residence contributes to market value. Finding comparable sales can be difficult when few nearby properties include two houses.

Buyers should not assume that the second home adds its full construction cost to the appraised value. Its legal status, size, condition, and usefulness to local buyers all matter.

Ask About Income and Future Use

A buyer may hope to rent the second residence to offset monthly expenses. Whether anticipated rental income can be considered for mortgage qualification depends on the loan program, documentation, and the buyer’s circumstances. Income should never be assumed before the lender confirms eligibility.

Before making an offer, ask for permits, floor plans, utility details, and records describing the second structure. Share them with your mortgage professional early. A property with two houses may offer valuable flexibility, but confirming how it will be financed is the best way to keep that opportunity from becoming a closing surprise.
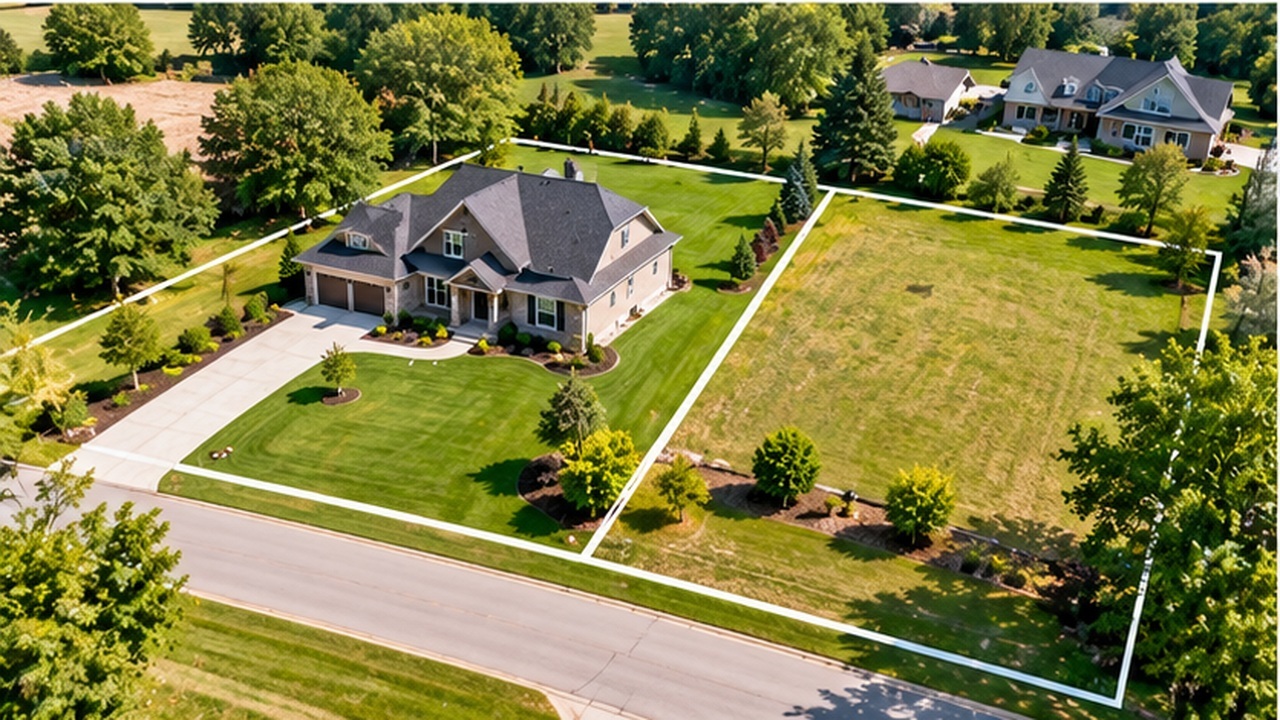
Why a Mortgage Lender May Question a Property With More Than One Parcel

Imagine finding a beautiful home that comes with an extra piece of land next door. Perhaps the additional lot provides more privacy, a larger backyard, or room for future improvements.
While this may sound like an attractive bonus, purchasing a home that includes multiple parcels can introduce mortgage questions that buyers might not expect.

What Does It Mean to Have Multiple Parcels?
A parcel is a legally identified piece of land, typically assigned its own property identification number by the local taxing authority.

Most residential properties consist of one parcel containing the house and surrounding land. However, some homes are marketed with two or more parcels that are being sold together.

For example, a seller might own a house on one parcel and an adjoining vacant lot on another. The two properties may function as one large yard, even though they remain legally separate.

This distinction can matter when a buyer applies for mortgage financing.

Why the Property Configuration Matters
Mortgage lenders need to understand exactly what property will secure the loan.

When multiple parcels are involved, the lender may need to determine whether the parcels can be included in the same mortgage transaction and whether the arrangement meets the loan program’s requirements.

Questions may arise about whether the parcels are contiguous, how they are legally described, and whether the additional land has separate development potential.

The lender may also review whether any parcel contains improvements, structures, or uses that could affect residential financing eligibility.

Simply advertising two parcels together does not automatically mean they can be financed as one property.

The Appraisal May Require Additional Review
An appraisal evaluates the property being offered as collateral for the mortgage.

When a home includes additional land, the appraiser may need to determine how that land contributes to the property’s overall market value.

A separate parcel does not necessarily increase the appraised value by the amount a buyer might expect.

For example, an adjoining lot with limited access or development restrictions may have a different market contribution than a parcel that can support another residence.

Comparable sales and local market conditions help determine how the additional land is valued.

Consider the Long-Term Implications
Buyers should also understand whether the parcels receive separate property tax bills, have different zoning classifications, or carry individual restrictions.

If they eventually want to sell the vacant parcel separately, they may need lender approval or a partial release of the mortgage lien, along with any required local approvals.

Before making an offer, buyers should ask for the parcel identification numbers, legal descriptions, and available property records.

Owning extra land can provide valuable flexibility, but buyers should confirm how that land affects their financing and future plans. Understanding the legal and mortgage implications early can help prevent unexpected complications before closing.

What Happens When the Seller Has Not Paid Off a Home Improvement Loan?

A newly installed roof, upgraded windows, or modern heating system can make a home more attractive to buyers. However, what happens when the seller is still making payments on those improvements?

Depending on how the work was financed, an outstanding home improvement loan could affect the sale, the title review, and even the buyer’s mortgage closing.

Not All Home Improvement Loans Work the Same Way
Homeowners finance improvements through several methods, including personal loans, home equity loans, contractor financing, and property-assessed financing programs.

Some financing arrangements are unsecured, meaning the loan is based primarily on the borrower’s credit rather than a claim against the property.

Others may be secured by the home, creating a lien or another obligation that must be addressed during the sale.

This distinction matters because an unpaid personal loan does not necessarily interfere with transferring ownership, while a loan secured by the property may need to be resolved before closing.

Why the Title Search Matters
During the mortgage process, a title search helps identify recorded liens, ownership issues, and other claims affecting the property.

If the seller financed a renovation through a loan secured by the home, the outstanding balance may appear in the title records.

The title company and closing professionals will determine what must be paid or released to provide the title required for the transaction.

In many cases, the seller can use proceeds from the sale to pay off an outstanding secured loan. However, the payoff amount and necessary documentation must be obtained before the transaction is finalized.

Special Considerations for Property-Assessed Financing
Some energy-efficient improvements are financed through Property Assessed Clean Energy, commonly called PACE, programs.

Unlike traditional personal loans, these obligations may be collected through property tax assessments.

Depending on the program and mortgage requirements, an outstanding PACE assessment can create additional questions about lien priority, payoff obligations, and whether the financing arrangement is acceptable.

Buyers should never assume that an obligation can simply remain attached to the property without affecting their mortgage.

What Buyers Should Ask Before Closing
If a seller advertises recently completed improvements, buyers can ask whether the work has been fully paid for.

They should also find out whether any financing arrangements, warranties, or service agreements are connected to the improvements.

The goal is not to discourage buyers from purchasing homes with recent renovations. Instead, it is to make sure that the financial obligations associated with those improvements are clearly understood.

A beautiful renovation can add appeal to a property, but the paperwork behind it matters too. Addressing outstanding financing early helps protect the transaction from unexpected delays and gives buyers greater confidence about what they are purchasing.