Why a Shared Well Can Complicate a Mortgage Approval
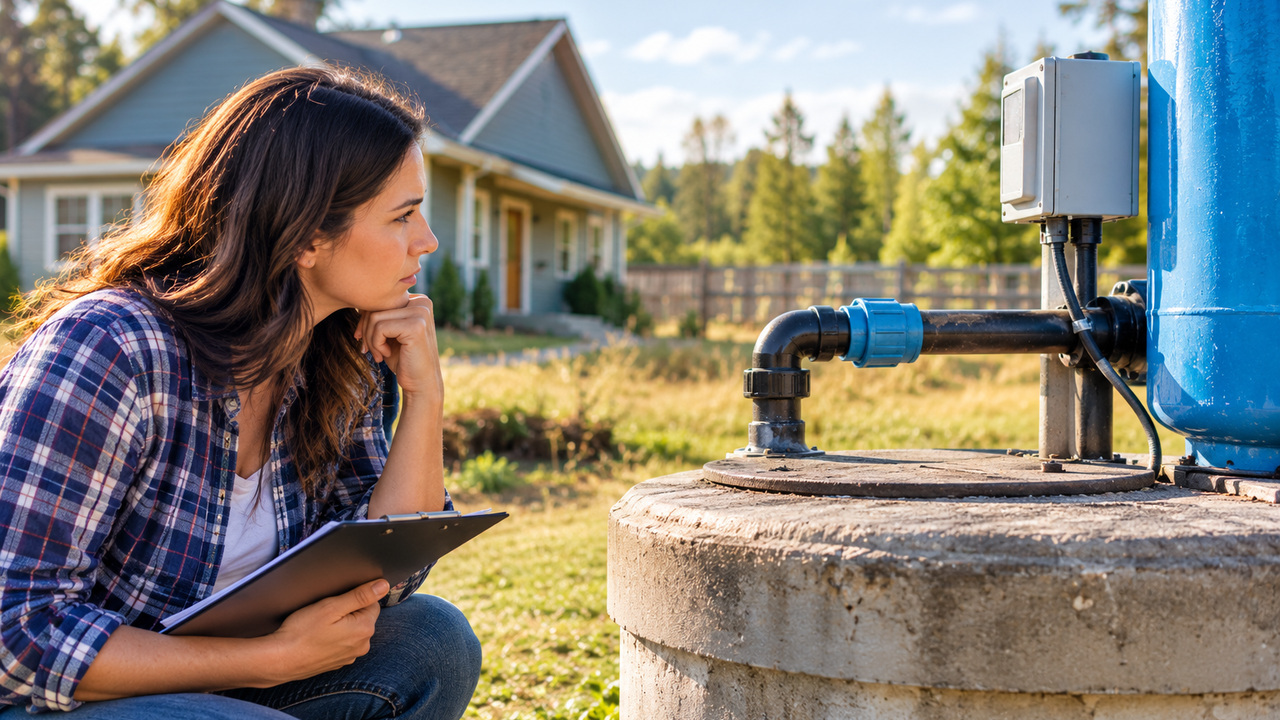
Buying a home with a private well can feel straightforward until you discover that the water source is shared with a neighboring property. Shared wells are common in some rural and semi-rural communities, but they can introduce questions that buyers of homes with municipal water may never encounter. A lender may need to understand not just whether the water works today, but whether the property has a dependable legal right to use it in the future.

A Shared Water Source Creates Shared Responsibilities

When two or more homes rely on the same well, ownership and maintenance responsibilities may be divided among the property owners. One household might have the well equipment on its land while another depends on a pipeline crossing the property line. That arrangement can work well for years, especially when neighbors cooperate. Problems can arise, however, if there is no clear agreement about repairs, electricity costs, access, or what happens when someone sells.

Lenders May Ask for Written Documentation

Depending on the loan program and property circumstances, a lender may request a recorded shared-well agreement or other documentation establishing access and responsibilities. The agreement may address who can use the well, who pays for upkeep, how repairs are approved, and whether each property can continue receiving water if ownership changes. Requirements vary, so buyers should avoid assuming that a handshake arrangement between neighbors will satisfy a lender.

Water Quality and Supply Still Matter

A shared-well agreement does not replace questions about the water itself. A lender, appraiser, or local authority may require information about water quality or whether the system can adequately serve the connected homes. Testing requirements can depend on the loan type, local rules, and property conditions. Buyers may also want to ask about the age of the pump, past interruptions, and whether the system has enough capacity during heavy use.

What to Check Before You Commit

Ask early whether the property uses a private well, a shared well, or a community water system. If it is shared, request copies of existing agreements and find out where the well and water lines are located. Ask who pays the electric bill, whether there is a maintenance fund, and how emergency repairs are handled. A title professional or real estate attorney may help clarify whether necessary access rights are documented.

It is also wise to raise the issue with your lender before the transaction is far along. Discovering a missing agreement shortly before closing can create delays while the parties gather signatures or resolve ownership questions.

A home served by a shared well is not automatically difficult to finance. The key is making sure the water supply is reliable and the arrangement is clear enough for everyone involved. A little investigation early in the buying process can prevent a surprisingly complicated issue from surfacing just as you are preparing to move.
Can a Home-Based Business Affect Your Mortgage Approval?

A home office, a small workshop, or a room used to meet clients may seem like a normal part of modern homeownership. But when you apply for a mortgage, the way a property is used can matter just as much as how it looks. A home-based business does not automatically prevent financing. The questions usually involve whether the property remains primarily residential, whether its use is permitted, and whether the lender can comfortably evaluate it as a home.
Residential Use Comes First

Most standard residential mortgage programs are designed for properties used primarily as residences. Working remotely from a spare bedroom is generally different from operating a storefront, manufacturing facility, or business that occupies most of the building. Lenders may look at the amount of space devoted to business activity, whether customers visit regularly, and whether the property’s layout still resembles a typical residence.

A detached workshop or converted garage may raise additional questions. For example, a garage with a workbench is different from a building outfitted as a full commercial operation. The distinction is not simply whether someone earns money there. It is how the business use affects the property’s character and marketability.

Zoning and Permits Matter

Local rules can determine which businesses are allowed in residential neighborhoods. Some communities permit low-impact home occupations but restrict signs, employee parking, customer traffic, noise, or storage. A business that violates local zoning requirements may create concerns for a lender or appraiser.

Changes to the property can matter, too. If a homeowner removed a kitchen, built a separate entrance for clients, or converted living space into specialized commercial rooms, the lender may ask whether those changes were properly permitted and whether the property can readily function as a residence.

What the Appraiser Evaluates

An appraiser considers the property as it exists, including its layout, condition, and appeal to typical buyers in the area. Unusual business improvements do not necessarily add the same value that they cost to install. Highly specialized features may even make comparable sales harder to identify.

The appraiser may also note whether the business area can be converted back to ordinary residential use. A flexible home office often presents fewer valuation questions than permanent alterations designed for a narrow commercial purpose.

Income Is a Separate Question

If you own the business, your self-employment income may require additional documentation. That is a borrower qualification issue, separate from whether the property itself is acceptable collateral. A lender may review tax returns, business financials, or other records to evaluate qualifying income, depending on the loan program.

Questions to Ask Before You Buy

Ask how the property is zoned, whether business-related improvements have permits, and whether any homeowners association limits commercial activity. Share the intended use with your mortgage professional early, especially if the business requires dedicated facilities or frequent visitors.

A home-based business and a residential mortgage can often coexist. The safest approach is to confirm that the property remains suitable for residential financing before relying on an assumed approval timeline.

How Leased Solar Panels Can Affect Your Mortgage Approval

Solar panels can make a home attractive to buyers who want to manage electricity costs. But the panels on a roof are not always owned by the seller. When a solar system is leased or covered by another third-party agreement, buyers may need to review additional paperwork before their mortgage can be finalized.

Owned and Leased Systems Are Different

With an owned solar system, the homeowner generally owns the equipment, although there may still be a loan secured by the system or property. With a lease, a separate company typically owns the panels while the homeowner pays to use them.

A power purchase agreement is another arrangement in which the homeowner may pay for electricity generated by equipment owned by a third party.

These distinctions matter because a buyer may be asked to assume a contract rather than simply acquire equipment as part of the home purchase.

Why Mortgage Lenders Review the Agreement

A lender needs to understand whether the solar arrangement creates ongoing payment obligations, affects title, or gives another party rights involving the property.

Depending on the loan program, the lender may request the solar lease, payment terms, transfer requirements, and documentation about any recorded notices or security interests. The appraiser may also need to treat leased equipment differently from panels owned outright.

A solar contract does not automatically prevent mortgage approval, but missing paperwork or unclear terms can slow the process.

What Happens When the Home Is Sold?

Some solar agreements allow a qualified buyer to assume the existing contract. Others may offer a buyout or require the seller to complete steps before ownership changes.

Buyers should ask whether the provider must approve the transfer, whether payments can increase, how long the agreement lasts, and who handles maintenance or roof-related work. A low introductory payment is only one part of the financial picture.

Look Beyond the Electricity Bill

Before making an offer, request copies of the full solar agreement and recent utility bills. Find out whether there are production guarantees, insurance requirements, roof access provisions, or costs associated with removing and reinstalling panels.

Share the documents with your mortgage professional and closing team as early as possible. It is also wise to confirm who will be responsible for any remaining obligations after closing.

Solar panels may offer real benefits, but a lease is a continuing contractual commitment. Understanding that commitment before purchasing helps buyers evaluate the total cost of the home and avoid unexpected financing complications.