How to Financially Prepare for a Growing Family
Buying a home is often one of the first major steps people take as they prepare for a growing family. Whether you are expecting your first child or planning for the future, it is important to think beyond today’s budget and consider how your financial needs may change over time. Preparing in advance can help you feel more confident as your family grows and your priorities evolve.

Review Your Monthly Budget

A growing family often brings new expenses, including childcare, healthcare, clothing, education, and everyday household costs. Before making a home purchase, take a close look at your monthly budget and consider how these additional expenses may affect your finances. Choosing a home that allows room for future costs can provide greater long-term financial stability.

Build a Strong Emergency Fund

Life is full of unexpected events, and having emergency savings becomes even more important when your family grows. Financial experts often recommend maintaining several months of living expenses in a readily accessible savings account. This reserve can help cover unexpected medical bills, home repairs, or temporary changes in income without creating unnecessary financial stress.

Consider Your Space Needs

Think not only about your current lifestyle but also about what your family may need in the coming years. Extra bedrooms, flexible living spaces, nearby parks, quality schools, and safe neighborhoods may become increasingly valuable as your family grows. Planning ahead may reduce the need to move again sooner than expected.

Protect Your Financial Future

As your responsibilities increase, it is also a good time to review your insurance coverage, create or update a will, and consider life insurance if appropriate for your situation. These important financial planning steps can help protect your family while providing additional peace of mind.

Preparing for a growing family involves more than finding a larger home. It means creating a financial plan that supports your future goals while allowing you to enjoy the exciting journey ahead. Thoughtful planning today can provide greater confidence and stability for many years to come.
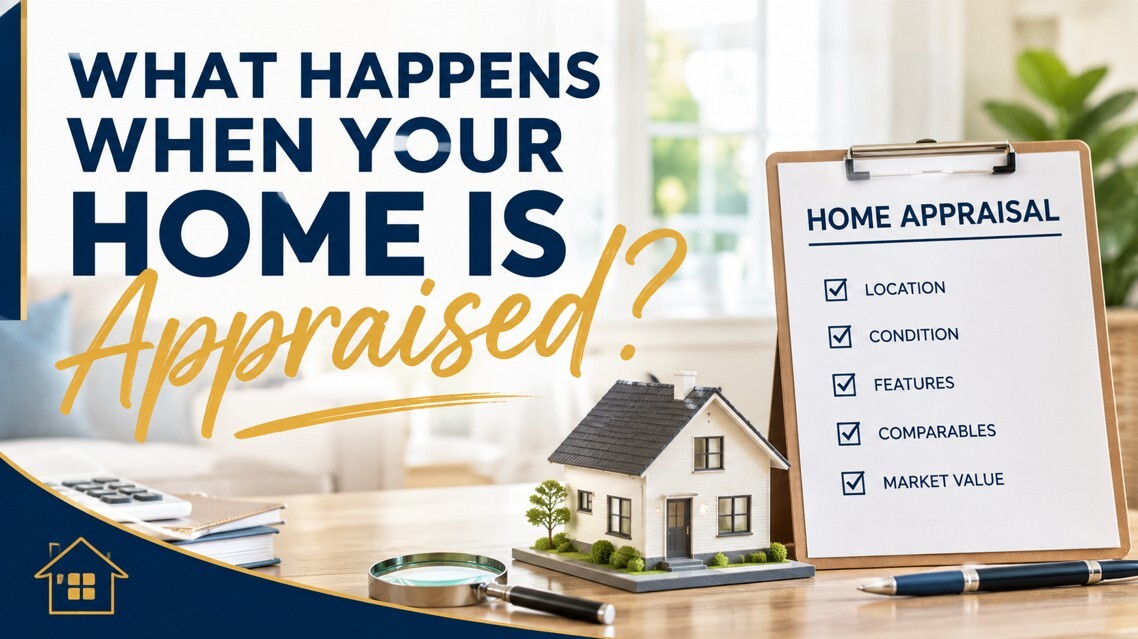
What Happens When Your Home Is Appraised?

Buying a home involves several important steps, and one of the most significant is the appraisal. While buyers often focus on inspections, financing, and closing dates, the appraisal plays a key role in the mortgage process. Understanding what happens during an appraisal and why it matters can help you feel more confident as you move toward homeownership.
What Is a Home Appraisal?

A home appraisal is an independent professional opinion of a property’s market value. Your lender orders the appraisal to help confirm that the home’s value supports the amount being borrowed. The appraiser is a neutral third party whose job is to evaluate the property’s condition, features, location, and recent sales of similar homes in the area.

What the Appraiser Looks For

During the visit, the appraiser evaluates both the interior and exterior of the home. They consider the home’s size, floor plan, condition, upgrades, lot size, and overall appeal. They also compare the property to recently sold homes with similar characteristics to determine a fair market value.

What Happens After the Appraisal?

Once the appraisal is complete, the lender reviews the report. If the appraised value meets or exceeds the purchase price, the loan process usually continues as planned. If the appraisal comes in lower than the agreed purchase price, your real estate agent and mortgage professional will discuss the available options. Depending on the situation, the buyer and seller may renegotiate the price, the buyer may choose to contribute additional funds, or other solutions may be explored.

Why the Appraisal Protects Everyone

Although buyers sometimes worry about the appraisal, it serves an important purpose. It helps ensure that both the buyer and lender are making a sound financial investment based on the property’s market value. This added layer of protection benefits everyone involved in the transaction.

An appraisal is not simply another item to check off your closing checklist. It is an important step that helps confirm the value of one of the biggest investments you will ever make. Understanding how the process works allows you to move through your home purchase with greater confidence and fewer surprises.

Why Annual Mortgage Checkups Are a Smart Financial Habit

Your mortgage is one of the largest financial commitments you will ever make, yet many homeowners rarely review it after closing. Just as annual physicals help you stay healthy, an annual mortgage checkup can help ensure your loan, insurance, taxes, and financial goals remain aligned. Spending a few minutes reviewing your mortgage each year can uncover opportunities to save money and avoid costly surprises.

Review Your Interest Rate
Mortgage rates change over time, and so do your financial goals. While refinancing is not the right choice for everyone, reviewing current market conditions can help you determine whether opportunities exist to lower your monthly payment, shorten your loan term, or access equity responsibly.

Check Your Escrow Account
Property taxes and homeowners insurance premiums often change from year to year. Reviewing your escrow statement helps you understand why your monthly payment may have increased or decreased and gives you time to prepare for adjustments before they affect your budget.

Evaluate Your Home Equity
As you make mortgage payments and home values change, your equity grows. Understanding how much equity you have can help you plan for future renovations, debt consolidation, or other financial goals. It also allows you to track the progress you are making toward full ownership.

Update Your Financial Goals
Life changes quickly. A new job, growing family, retirement planning, or paying off other debt may influence how your mortgage fits into your overall financial picture. An annual review is a good opportunity to make sure your home financing continues to support your long-term goals.

A mortgage should not be something you think about only when you buy or sell a home. A simple yearly review helps you stay informed, identify opportunities, and make confident financial decisions throughout your homeownership journey.