Personal CA-DRE #01455710 · NMLS #256707  |  Company CA-DRE #02075839 · NMLS #1777223

Blog

Veterans Day: Honoring Service and Understanding VA Home Loan Benefits
Veterans Day is an opportunity to recognize the men and women who have served in the United States Armed Forces. Their commitment deserves gratitude that extends beyond a single day. For veterans, active-duty service members, and eligible surviving spouses who are considering homeownership, it is also a meaningful time to understand a benefit that may help them purchase or refinance a home: the VA home loan program.

What a VA Home Loan Does

A VA home loan is generally made by a private lender and backed by a guaranty from the U.S. Department of Veterans Affairs. The guaranty helps eligible borrowers access financing under terms that can differ from conventional mortgages. For many eligible buyers, a VA-backed purchase loan may offer a no-down-payment option, provided the sales price does not exceed the appraised value and the borrower meets lender requirements.

VA loans generally do not require monthly private mortgage insurance. That can make a difference when comparing monthly housing costs. However, a VA funding fee may apply, and certain borrowers qualify for an exemption. Closing costs, property taxes, homeowners insurance, and other expenses still need to be considered.

Eligibility Is the Starting Point

Military service alone does not automatically establish approval for a particular mortgage. Borrowers typically need a Certificate of Eligibility to confirm their VA loan benefit, and the lender reviews income, credit, debts, and the property. Service requirements and surviving-spouse eligibility rules can vary. A lender experienced with VA financing can help explain the steps and request the appropriate documentation.

The Property Matters Too

VA financing is intended for eligible residential use, and the property must meet applicable appraisal and minimum property requirements. An appraisal evaluates value and certain property conditions; it is not a substitute for a comprehensive home inspection. Buyers should still consider an independent inspection so they can understand the home’s condition before closing.

A Thoughtful Way to Explore the Benefit

If you are eligible and thinking about buying, start by asking a qualified lender for a comparison of VA and other available loan options. Look at the interest rate, estimated monthly payment, cash needed at closing, funding fee if applicable, and total borrowing costs. The right choice depends on your circumstances, not simply the loan label.

Today, we honor veterans and their families for their service and sacrifice. Understanding the benefits earned through that service is one practical way to support informed decisions about the next chapter of homeownership.
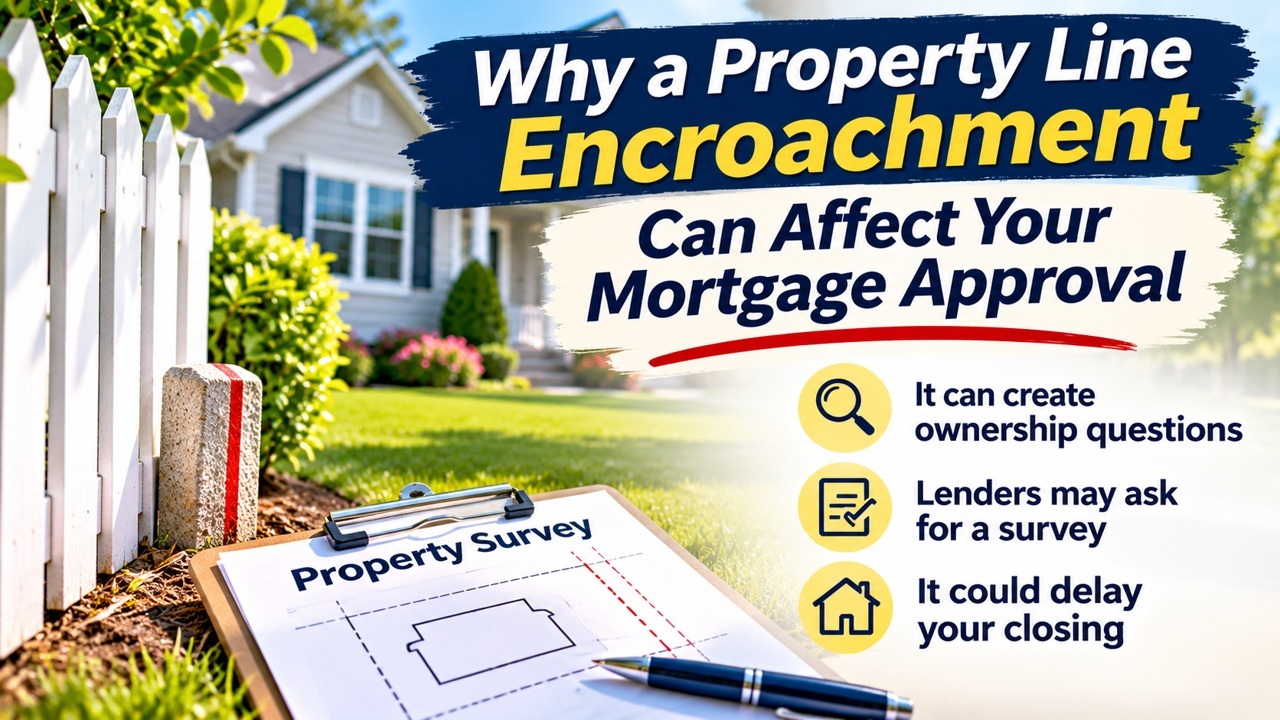
Why a Property Line Encroachment Can Affect Your Mortgage Approval

A backyard fence, detached shed, or concrete patio may seem like a straightforward feature of a home. But what happens when part of that structure crosses the legal property line? Buyers sometimes discover this issue during the title or survey review, just as they are preparing to close. Known as an encroachment, it can raise questions that go beyond neighborly disagreements and may affect the mortgage process.
What Is an Encroachment?

An encroachment occurs when a structure or improvement extends onto land owned by someone else. Common examples include a fence installed several feet over the boundary, a driveway that overlaps an adjacent parcel, or a shed built partly on a neighbor’s lot. The opposite can happen too: a neighbor’s structure may extend onto the property you plan to buy.

Not every apparent boundary issue is an actual encroachment. Landscaping, old fence lines, and informal neighborhood arrangements can make property boundaries difficult to judge by sight alone. A survey and the recorded property description can help clarify what is happening.

Why It Can Matter to a Lender

A mortgage lender wants to understand whether the property offers acceptable security for the loan. A significant encroachment may affect the property’s marketability, value, or the owner’s ability to use part of the land. Title insurers may also need to determine whether they can provide the coverage required by the lender.

The seriousness depends on the facts. A small fence issue may be treated differently from a garage that extends onto another parcel. The location of the improvement, local rules, loan program, and available documentation all matter. An encroachment does not automatically make a home ineligible for financing, but it may prompt additional review.

What Buyers Should Ask

If a survey or title report identifies a possible encroachment, ask your real estate agent and title professional to explain exactly where it is and what documents exist. Find out whether the parties have a recorded agreement, easement, boundary adjustment, or another legally recognized solution. Ask the lender whether the issue needs to be resolved before closing.

Avoid relying solely on a seller’s assurance that the neighbors have never complained. A friendly arrangement today may not answer questions about future ownership or resale. Depending on the situation, a real estate attorney or licensed surveyor may need to help determine the next step.

The best time to uncover a boundary problem is before the final days of a transaction. Reviewing the available records early can help buyers understand the risk, evaluate possible solutions, and keep an unexpected property line issue from becoming a last-minute mortgage surprise.

What’s Ahead For Mortgage Rates This Week – November 9th, 2026

With a relatively light week for economic releases, the primary focus of the economic landscape is the nonfarm payroll report, which has shown a positive trend over the last few releases. This should help consumers keep up with current inflation levels, although the Federal Reserve has remained firm in its commitment to reaching its 2% inflation target.

The unemployment rate has also continued to trend downward after reaching a high of 4.5% last year. The economy continues to be reported as healthy, but with ongoing geopolitical conflicts and other uncertainties, inflation remains a major concern for many. The likelihood of the Federal Reserve maintaining current interest rates remains high.

Unemployment Rate
The US unemployment rate dropped to 4.2% in June 2026, down from 4.3% in May and below expectations, as many people left the workforce. The number of unemployed individuals fell by 213,000 to 7.09 million, while total employment declined by 507,000 to 162.26 million. The labor force contracted by 720,000 to 169.36 million, with the participation rate falling to 61.5%, its lowest level since March 2021. The employment-population ratio also dipped to a four-year low of 59.0%. The broader U-6 unemployment rate, which includes discouraged and underemployed workers, decreased to 7.9% from 8.1%.

Nonfarm Payroll
The US economy added 57K jobs in June 2026, well below the downwardly revised 129K in May and forecasts of 110K. This was the lowest monthly job gain in four months, but it was still roughly in line with the average monthly change over the prior 12 months (+36K). In June, employment continued to trend upward in professional and business services, social assistance, and health care. Employment in leisure and hospitality declined.

Primary Mortgage Market Survey Index

  • 15-Year FRM rates saw a decrease of -0.03%, bringing the current rate to 6.57%.
  • 30-Year FRM rates saw a decrease of -0.06%, bringing the current rate to 7.18%.

MND Rate Index

  • 30-Year FHA rates saw a decrease of -0.08%, with the current rate at 6.82%.
  • 30-Year VA rates saw a decrease of -0.07%, with the current rate at 6.84%.

Jobless Claims
Initial jobless claims came in at 194,000, compared to the expected 200,000. The previous week’s figure was 200,000.

What’s Ahead
The week ahead is expected to be relatively light, with the Federal Reserve scheduled to announce its interest rate decision midweek.